• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University. 

Want More Money For College? What the $%#! Are FAFSA and EFC?

January 8, 2013 by Joe Saul-Sehy 22 Comments

Bill & Caitlin want to put their children through college, but like many people, they had other priorities. With three younger children, it’s been a difficult road to save for their oldest. Now Jennifer is a senior in high school, and they were in my office with the same look a football team has when they’re down by five points and have 50 yards to go with only 8 seconds left in the game.  Time for some drastic action.

Luckily, Bill & Caitlin had some room to work with to make their chances of aid better than they’d expected. We also made it easier for them to pay for college by making some changes to their overall financial plan.

But first, there were some crucial terms Bill & Caitlin didn’t understand that we had to define. Their whole college aid strategy would be predicated on knowing the rules of the game, and off these rules were wrapped up the terms “FAFSA” and “EFC.”


The FAFSA


The Free Application for Federal Student Aid is more than the name implies. Although this is the government’s financial aid program to apply for the Pell Grant, it also opens up nearly all need-based aid programs you’ll ask for in traditional college programs. Sure, Bill & Caitlin had heard of the FAFSA form before, but they were about to make a critical mistake: they weren’t going to fill it out because the chances of them receiving federal government aid was highly unlikely.

That would be a huge mistake.

Don’t avoid the FAFSA in your search for college funding options. Here’s a good way to think about financial aid programs (although schools and states wouldn’t present the information this way): schools will not give you financial aid until you bleed the state. The state won’t give you financial aid until you bleed the feds. For this reason, EVERYONE works through the FAFSA form. While most people will be denied a Pell Grant, this is also the form to apply for subsidized and unsubsidized student loans, and unsubsidized student loans programs are open to nearly everyone. It’s also the way to apply for almost every need-based aid through states and schools.

Key point: Fill out the FAFSA form, even if you think you won’t receive any aid. When? Start now.


EFC


This is another “biggie.” Expected Family Contribution (or EFC), is the amount the government says you should be expected to pay out of pocket for school before aid programs kick in. Bill and Caitlin were making some huge mistakes in their money management that was actually costing them EFC dollars.

Your need will be based on the difference between the cost of the college and the amount of your EFC.

            Cost of school minus EFC = need

Based on your need, your school’s financial aid officers will create an aid package.

It’s important to remember that the acronym is eFc (expected FAMILY contribution, not ePc (expected PARENT contribution). Schools will look at the income and assets of the student as well as parents. They’ll also examine how many other family members there are and the number that are also attending college.


Schools may not have the same EFC calculation. There are two. You should ask which your favorite institutions use:

–          Federal EFC calculation. This is the most used number and is determined using the FAFSA.

–          Institution EFC calculation. This calculation is used by individual schools to determine their own EFC. While they may rely on the FAFSA as well, individual schools may have additional criteria they consider when determining aid packages.


Takeaway Information


So, Bill & Caitlin had a ton to consider, but a few points were obvious already:

–          Understanding the basics of the FAFSA before filling it out would help them calculate ways to better reflect their true EFC.

–          Ask schools what EFC calculation each uses and find out any institutional discrepancies from the national EFC calculation BEFORE applying for financial aid.
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.
joesaulsehy.com/

Filed Under: College Planning

Stock Market Punishment: The First Lesson of 2013

January 7, 2013 by Joe Saul-Sehy 38 Comments

The podcast team is giving the interns a well-deserved week off, so lucky reader….YOU get a FREE extra blog post from Average Joe. I know. Pinch yourself. It’s real. Almost like our awesome rare Saturday post this week.

Look at what the media did to you again.

The sky is falling! Fiscal cliff! Doom! Stock market will be in shambles! Hide your children!

Big ratings for the financial channels, huh?

If you listened and moved your money out of the market, it destroyed your chances for a great return in 2013.

MAYBE you’ll recover if you jumped out before the big two-day run up in stocks. The chances, though, are against you: historically, if you miss the 10 best days in the stock market, you lose about 5.18%, or nearly half your return for the year. If you paid trading fees to avoid the “fiscal cliff disaster,” this only exacerbated your problem.

Here’s what the panicked investor missed in the S&P 500 last week:

December 31: 1.7%

January 2: 2.5%

January 3: –.03%

January 4: .05%

In short, if you missed two days last week you lost out on 4.2%. Those types of returns don’t come around often.

By the way, don’t go in the comments and tell me that “all you lost was a little time….” go back and read the stats above first. You lost a ton.


let’s calculate the cost of listening to the media on this one


Suppose you’re 25 years old and you have managed to save $10,000 into your 401k plan. You lost out on $420. Sounds like no big deal, right?

Let’s use the rule of 72 to determine just how much you really lost:

The rule of 72 says that if you divide the interest rate you think you’ll achieve into 72, you’ll come up with the approximate number of years it’ll take your money to double. Cool, huh?

Assuming that you wanted this money for retirement (401k, right? That’s not your “mad money” account….I hope), we’ll use age 70 for your withdrawal. We’ll also use a realistic return assumption of 8%.

8% / 72 = 9 years for your money to double.

So, that $420 you lost wasn’t really $420, was it?

It would have doubled when you were 34, 43, 52, 61, 70.

Your “little” $420 wasn’t $420. By 32 it was $820. At 41 it was $1,640. By age 50 you’d lost $3,280. At 59 the gap was $6,560. When you went for the money at 69 you had $13,200 less.


it gets worse


If you’re 30 and gambled $50,000 that the market would tank, it’s uglier. Let’s also use 9% rather than 8%, since people looking long term historically have used 10% as their assumption (which I believe is too high, BTW).

Check out what more money and a “little” one percent difference do to your loss:

Rule of 72 = 8 years for money to double.

Funds double at 38, 46, 54, 62, 70

$2,100 lost during two day run-up in market.

= 4,200 loss at 38, 8,400 loss at 46, 16,800 at 54, 33,600 at 62 and

…$67,200 at age 70.

On our “What Did We Learn in 2012” podcast, expert after expert told you the same thing: don’t listen to national media finance porn and don’t chase short term results.

If you did, I’m going to play Dr. Phil now: How’s that workin’ out for ya?


Photo: Joe Shlabotnik

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: investing news, Retirement, risk management, successful investing Tagged With: best 10 days in stock market, lessons of 2013, stock market 2013 lessons, stock market punishment

Saturday! Let’s Play Money

January 5, 2013 by Joe Saul-Sehy 6 Comments

Tired of all the New Year’s lists? So am I (not that there weren’t good ones….I’m just over it now).

So, I bring you the MOST AWESOME New Year’s List of all.

Cheers.

j.


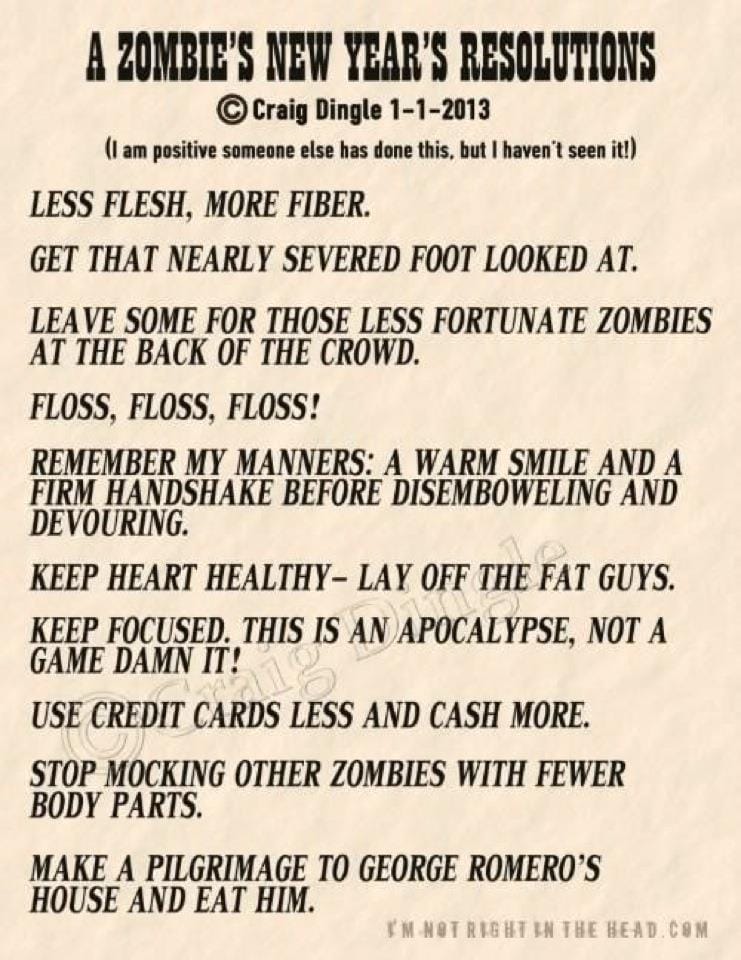
A Zombie's New Year's Resolutions list, including "Less flesh, more fiber" and "Use credit cards less and cash more"


Photo: Jimmiehomeschoolmom

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: irrelevant stories

5 Simple Steps to Kick 2013 Into High Gear

January 2, 2013 by Joe Saul-Sehy 44 Comments

Happy 2013, everyone!

It’s time to take yourself a little more seriously and step up your game. My cousin, a year younger than me, had major heart surgery a couple weeks ago and nearly lost his life on the operating table. Not to be all melodramatic, but it was another close-to-home reminder that time is a finite beast. If you’re going to leave your mark on the world (or just on your little private Idaho), 2013 is the time to make changes.

Here’s the gameplan we’d use when practicing financial planning with clients back in “the day” and it’s also what I’m using this year to shift up a gear:

1)   Write out clear, actionable goals. I like Maria at The Money Principle’s post about themes. Start with an idea generally of what you want to do, then drill down toward specific tasks.

My 2013 theme is about tying up loose ends and focusing harder on core tasks. I haven’t yet crystalized completely the theme (it should be more succinct than what I have so far), but that’s not bad news. I’ve been thinking about it constantly, and this action gets the right thoughts in my little noggin’.

My main goals are simple: I have the first draft of a book written, and I’ve let it sit for about 9 months. Why? I have no idea. Other priorities. But now’s the time to finish that project. I’ve run marathons now for two years. I’d like to run one faster than ever. I’d also like to try an ultramarathon. I need to focus on cooking healthier food at home and have a more regimented plan. On the website side, we’ve talked about creating some products. These need to be launched in 2013.

2)   Direct deposit to your savings account. Everyone direct deposits money into their checking account…and immediately drains it. Reconfigure your system so that you direct deposit to savings. Manually move money to live on over to your checking account.

While this seems like a little step, it’s a huge change. Now you’re saving automatically and having to think every time you spend money. You’re a conscious consumer, rather than an auto-spender.

3)   Protect your downside. I know this for a fact: bad stuff that you don’t expect will happen in 2013. I don’t know where it’ll come from, so the best course of action is to look for Achilles Heels and apply duct tape. Do you have an emergency fund? Is your insurance up-to-par? Is the budget tight?

I need to adjust Cheryl’s life insurance (adjusted mine in 2012). Our will is now six months from being out-of-date (my children will be 18 years old…how the hell can that be? They were just babies yesterday….). I also have to begin “landing the plane” with my kid’s investment funds, so they’re ready when and if I need them for college expenses.

It’s also time for me to get home and auto quotes again. For some, checking out Insure 4 a Day may be a good idea. They offer a variety of cheap short term car insurance options dependent on your requirements.

4)   Focus on energy, not time. I agree with Jim Loehr and Tony Schwartz in their book The Power of Full Engagement on this one: the key to optimum performance is to manage your ability to crank stuff out. As workers, we’re like tennis players: we compete year-round. It stands to reason that we can’t be great every moment of every day. We should gear up for those times when there are “big tournaments” in our life and focus on those days.

I’m working on a model day that better uses my energy and shelters that time I need for key tasks. I generally experience great creativity in the morning and low energy around 3 pm, so I’m reconfiguring my day to take advantage of that morning time and guard against the afternoon letdown. I’m also focusing more on my diet to avoid those crashes (just as soon as I finish these chocolates….).

5)   Create surround sound. The best way to stay motivated is to surround yourself with people, books and podcasts that keep your mind on those activities that’ll help you achieve your dreams. Schedule meetings with your planning partners, spouse, and close mentors. Don’t just say “I’ll talk to people more often about my plans.” That doesn’t happen, does it? Set a time in your calendar and stick to it.

We created the podcast for this reason. I enjoy casual talk about subjects I’m interested in, not hard core discussions. I couldn’t find many chatty money podcasts (Planet Money is probably the closest I’ve found), so we created one. If you’ve listened to our show you know: it’s more about equating money with fun and less about deep drilling.

Biographies work well for me, too, to create surround sound. I don’t know why, but I particularly love books about chefs. Maybe it’s because they have to be in-the-moment so much. I loved Kitchen Confidential by Anthony Bordain (don’t read this book if you don’t like foul language and discussions about illegal activities). Currently I’m polishing off Restaurant Man by Joe Bastianich. Both of these are great looks into the world of business, written passionately by someone who knows their craft inside-out.

This list could be 100 points long, but if you practice those five above as you walk into 2013, you’re going to move faster, with more energy, and with fewer distractions.

ON that note, how about $100 Amazon money or cash to start your year off right! That’ll buy a bunch of groceries, books or mp3 players…..

Photo: TheBusyBrain


a Rafflecopter giveaway

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: budget tips, Cash Reserve, money management, Planning

What Did We Learn in 2012? (…and a look forward into 2013): Two Guys and Your Money Episode 24:

December 31, 2012 by Joe Saul-Sehy 13 Comments

Have shows come automatically to your iPod! Use the 2 Guys iTunes page here.

Listen to shows on your smartphone! Try the Stitcher app here.


Here’s the perfect way to end 2012: one last episode of Two Guys & Your Money!

If you’re interested in making more OR saving more in 2013, we’ve got you covered in this episode. Our mission this week was to ask the question: What should we have learned in 2012?

Big thanks to Laurie Ruettiman of The Cynical Girl fame, as well as Ornella Grosz (Moneylicious), Paula Pant (Afford Anything), Lance (Money Life & More), as well as our usual team of PK (DQYDJ.net), Dominique Brown (Your Finances Simplified) and Barbara Friedberg (Barbara Friedberg Personal Finance).


Show Notes:

<> Top 10 Dumbest Financial Stories of 2012

<> Laurie Ruettiman: What should we have learned about work in 2012?

<> PK:  2012 highlights

<> Ornella Grosz

<> Paula Pant

<> Lance: Money Life & More

<> Barbara Friedberg

And:

<> Dominique Brown

<> Top 5 Things OG & Joe learned in 2012

<> Movies: OG: Jack Reacher, Joe: Playbook Silver Lining


Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Podcast

Post-Holiday Distress: Did You Spend Too Much?

December 27, 2012 by Joe Saul-Sehy 27 Comments

Stop. Take a deep breath. That feeling of dread? It’s just the holiday spirit leaving your body with each passing breath. It’s your own fault… everyone knows not to look at the receipts on the day after!

If you were smart, you planned ahead. You created a holiday account at the beginning of the year so by the time November rolled around, you had cash on hand for cherry-picking the best deals.

If you were smart, you stuck to your budget and didn’t let stress, competition, irresistible deals, or last-minute price hikes to knock you off your plan. You made a list of people and charities you wanted to recognize, set a price per gift, stuck to your list, and got your shopping done early.

That’s if you were smart.

But if your candy cane and cookie euphoria is dissipating with every thought of your credit card statement, you’re not alone. It’s engrained in our culture: Thanksgiving is to overeating as Christmas is to overspending – lavish spending you’d never consider otherwise.

The pressure to GIVE is powerful; our senses may leave us entirely. When we shop, we anticipate the warm embrace and feeling of joy WE create when a gift is received. It’s awfully noble. But if you’re like me, today is the day you watch your kids and realize just how little use your gift will get (I will never buy a robotic pet again!).

So what’s next?

Budgets are fluid. They require constant reevaluation. If you overspent, it’s time to reconsider your budget for the coming months. You won’t be able to see any viable options without a clear picture. If you didn’t before, go back and write down what you spent.

Chances are, it’ll make you feel better. You’ll realize that, while you had a bad month for your budget, you aren’t completely out in the cold. Because, you see, most of the year… You were smart.

If you’re not feeling better, take solace knowing that it’s possible to mount a comeback.

A few years back, holiday spending tipped my credit card balances over the edge. I wasn’t smart. I thought I was – it makes sense to open up store credit cards to save 10%, right? Wrong. It wasn’t until too late that I realized I wouldn’t be able to make the minimum payments on so many cards.

I knew enough to see that with accumulating interest, everything I could afford to pay towards my various credit card bills would be going straight into the creditors’ pockets while my debt level remaind constant. Classic debt spiral.

What did I do? Consolidate. Debt consolidation sounds ominous, but it’s far worse for your credit to fall behind on payments. You can take advantage of low interest rates on balance transfers and merge your debt to one account, or seek a consolidation loan to pay off your principal balances. If you have good credit history, you may be able to achieve a lower interest payment or a longer payment period. Managable. You can handle that.

The moral of the story? I’ll say it again:

Stop. Take a breath. Enjoy what’s left of the holidays. You’ve got options.

Photo: TopGold

Thanks to Jennifer Willard for taking over the blog responsibilities today while Joe & OG search for more egg nog. Jennifer has a new blog, Crayons & Coins. She also writes for Credit Guard, a non-profit debt counseling company.

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: budget tips, Debt Management, money management Tagged With: Balance transfer, Christmas, credit card, Debt, debt consolidation, Payment

Holiday Games and Finance: What Can the Game “Dominion” Teach You About Money?

December 26, 2012 by Joe Saul-Sehy 22 Comments

While Joe’s playing Dominion with his sister, brother in law and spouse (we all l.o.v.e. this game at our house), Erin Shanendoah of The Dog Ate My Wallet fame holds down the fort at the blog. Hope you’re enjoying some quality family time like we are!

Dominion is hands down the favorite game in our house. Set up is minimal, and you can get through a 2 player game in as little as 10 minutes if both the players know the cards. Every game is different, which means that players need to be open to different kinds of strategies if they want a chance at winning.

Even forgetting that you have money within the game (copper, silver, gold & platinum(in the expansions)), you can learn a lot about finances from Dominion.

Every game is different. Just like every person’s financial situation is different. Because of this, there is no one strategy works for every game of Dominion, and there is no one size fits all solution to personal finance. You have to look at the cards that have been  dealt and figure out the best plan for this game, this situation. Only by responding to the uniqueness of each situation can you hope to consistently do well.

Multiple strategies can be viable options. My husband and roommate both love playing games, and for the most play well together. But they have different outlooks on life and will often see the exact same set of cards and come up with two completely different ways to win. They each go with the strategy that they are the most comfortable with.

Just because someone has a similar financial situation to you does not mean you have to both take the same financial strategy. Find what works for you and what you’re comfortable with, and you’ll have a much greater chance of “winning”.

Diversity is good. Too much is not. Currently, there is the base set and 7 expansions for Dominion. While you can play with as many expansions as you want, we’ve found the best games are limited to 3 sets- usually the base plus two expansions. 3 sets gives you lots of options, but you don’t lose the synergy between cards.

Diversifying your holdings financially helps mitigate your risk, but if you diversify too much, you lose the power of “buying in bulk” so to speak. (Average Joe and The Other Guy can both speak about this much more eloquently than me.)

Sometimes you just need more money. Other times, you need your money to work harder for you. Within Dominion, you use money to buy other cards. You can buy more money, action cards, or victory point cards. Sometimes, the best strategy is to use your money to buy more money, especially in the early stages of the game. But later, you’ll want to use that money to buy action cards. Those cards allow you to advance your strategy, hinder the strategy of others, and sometimes even buy the highest value victory card, even though you started the hand with only 2 coppers.

Early on in your life, often the best solution to money problems is just to get more–go out and work a second job, find a way to earn passive income, etc. But once you get to the point where you’re not struggling to pay the bills, you need your money to work for you. By making smart moves with your money, you can open new doors for yourself or your family, and eventually “win” the game by having a comfortable retirement. (I do hope that in real life, you won’t use your money to hinder others. That should be a game strategy only.)

Just sitting on money can slow you down. One might think the one strategy in Dominion that would work in every game would be to use your money to buy more money until you had enough to buy victory cards, and just keep doing that. It doesn’t work. While you obviously need victory cards to win the game, they don’t do anything else. You can’t spend them. You can’t take an action from them (well, in some expansions there are victory cards that have actions, but those are very special cases). Instead, they just take up valuable space in your hand and do nothing, slowing you down.

While sometimes it seems the safest way to save money is just to stick it in the recliner and sit on it, your money can’t grow that way. It can’t actually do anything for you. It’s a strategy that just slows you down.

The cards aren’t always your friends. There are good cards and bad cards in Dominion. There are cards that are good for the person who plays them and awful for others. There are thieve and militias, there are curses and witches. You can be forced to destroy your victory point cards or have a platinum stolen by the player to your left. Sometimes, you just get negative victory points. In order to win, you have to have a strategy to weather or eliminate the bad.

Bad things happen in real life. You need to have the tools to survive them. Sometimes it’s just in making smart decisions and protecting yourself. Getting yourself out of debt and carrying the right kinds and amounts of insurance can also protect you against the vagaries of the world.

Luck always plays a role, but it’s not everything. Because every player of every game of Dominion starts out with the exact same 10 cards, and a five card hand, there’s a limited number of opening hands you can have. But which one you get and how well it works for that particular game, is all a matter of luck. If two good strategies are going against each other, it’s really just going to be luck that decides the winner of the game. But it’s very rare for a well thought out strategy to lose to no strategy at all. Just depending on luck isn’t likely to win the game.

Some people start life luckier than others. Some people get lucky later on. And some people make their own luck by coming up with a well thought out strategy. And in life, it’s not really going to matter if you retire with $2 million while your buddy is ending with $2.1 million. You’ve both “won”.

Don’t forget to have fun. Dominion is a game. The husband and roommate are both competitive people and love to win. I care much more about enjoying the game. But I can’t enjoy the game if I feel ineffective. I will enjoy myself just as much putting together a strategy that comes “this close” to winning as I will winning the game. I will even enjoy a failed strategy if I find a single good combination within it.

How much money you die with matters only to the people you leave it too. You can’t use it anymore. Don’t put your life on hold just to reach some arbitrary savings goal. If you never take vacation until you’re 75 years old, are you going to be able to climb the island stairs at Tintagel? Yes, you want to save for the future and make sure you have enough to retire in comfort, but there’s no counting up victory cards at the end of your life, declaring you the “winner”, so make sure you have some fun along the way.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Investing, money management, Planning

Two Guys & Your Money 023: Better Work? Quality Trips to the Grocery Store?

December 24, 2012 by Joe Saul-Sehy Leave a Comment

Have shows come automatically to your iPod! Use the 2 Guys iTunes page here.

Listen to shows on your smartphone! Try the Stitcher app here.


I know what you’re thinking…you guys have been doing this for at least eight months….isn’t it time for a Best Of episode?

Your prayers have been answered.

Because both OG and I are “out of the office” for the next several days, we’re giving you the best gift ever: listening to our early episodes while we were still getting the hang of podcasting. I know. You are so welcome.


Show Notes

<> Open

<> Our favorite early interview: Julie Clow, author of The Work Revolution

<> Our favorite PK piece: which funds to remove first to spend?

<> Our favorite roundtable piece:

<> Our favorite Top 5:

TODAY is your last chance to enter our Mommy Millionaire giveaway. No, we’re not giving away a mommy millionaire. We’re giving away the book (just to clear up any ambiguity).

<> Favorite holiday movies:  OG: Elf  Joe: Christmas Vacation


Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Podcast

2 Guys and Your Money 022: Making Life an Adventure – The Hobbit episode

December 17, 2012 by Joe Saul-Sehy 4 Comments

Have shows come automatically to your iPod! Use the 2 Guys iTunes page here.

Listen to shows on your smartphone! Try the Stitcher app here.

Just like a certain film that appeared in box offices last weekend, we have an epic podcast for you this month. Not only do we have unbelievable guests, but the stories our regular contributors share about their adventures is equally as exciting.

Show Notes


<> Open – Our favorite motivational phrases

<> Natalie Sisson – Suitcase Entrepreneur – Biking Africa

<> Len Penzo – Getting the big raise: Check out Len’s companion piece at his blog.

<> Chris Klinke – Mountain climber – Walking Away from Six Figures

<> Dr. Dean – Running for public office

<> Let’s Give Something Away: Mommy Millionaire

Enter our giveaway here

<> Barbara Friedberg – Snagging a book contract

<> PK from DQYDJ – Avoiding TPS Reports and the Power of Automation

<> Jana from Daily Money Shot – Writing a Novel in 30 Days

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Podcast

Average Joe’s Friday Sing Along

December 14, 2012 by Joe Saul-Sehy 25 Comments

Welcome to our new feature. This will play on sporatic Fridays (read: whenever I feel like it).

Thanks for all the great emails about the Diary. Like everyone who writes (on the internet or elsewhere), I get frustrated sometimes and it’s great to have a place to just vent, you know? Plus, I like being able to share a few of the “secrets” we’ve learned over the first year of operating this thing, and it’s been fun going back in the time machine and looking at stats from a year ago.

That’s all I’ll say about that topic, because I created the Diary specifically because I knew there were people out there who’d be interested in my rants….but it isn’t the mission of this blog.

This weekend we pick up a new table for our dining room. Buying furniture always is a struggle for me. On one hand, I like having nice stuff, but on the other, I don’t want to pay for it. Call me the opposite of the US Government! If I were buying on credit or didn’t have the funds to do it, I’d definitely walk away from the transaction. BUT I do have the money available, we really haven’t spent much on the home this year, and it’s a nice upgrade SO we pulled the trigger.

You know your life is exciting when you spend a paragraph of the blog writing about your new table. Par-tay.

In better news, five minutes from now a good friend is picking me up to fly in his new plane to Dallas to watch our kids swim. I’ll post pictures on Twitter and Facebook.

Let’s get on with the show:


Some Wonderful Reading


Let’s start with Glen at Monster Piggy Bank. Sometimes I don’t know what to do with Glen. I called him “Crazy Man” one time and he questioned what that was about….then he gets all crazy with the tattoos and work posts. Of course he’s Crazy Man! Do you think people should be discriminated against at work because they have a visible tatoo? Check out the post.

There’s major congratulations in order. Kim at Eyes on the Dollar has knocked out $30k in debt. Momma said KNOCK YOU OUT!

While we’re talking congrats, Holly at Club Thrifty will now post twice monthly at Get Rich Slowly. Hey, Holly, when you’re a huge star, don’t forget us little people.

In my favorite travel journal, Reach Financial Independence, Pauline tells an awesome story about helping her employee get a new bike…and then decide that he isn’t that crazy about paying it off.

Mrs. PoP from Planting Our Pennies wins my award for Best Analytical Post of this list (an incredibly prestigious award). Check out how she turns discounted cash flow into numbers porn for us financial geeks.

Sam Dogen writes a thoughtful post at Untemplater about whether we should bail out student loan debt. If we decide that’s okay, let me know ahead of time. I have twins starting college in a year and I’ll just finance it all with public funds…..

Speaking of Crazy Man (and a guy who won’t fight me when I call him that…he wears it like a badge) Len Penzo answers the question “Credit or Debit” that’s so popular at retail outlets everywhere.

Finally, if my blogging friends haven’t seen it yet:  My friend Sicorra at Tackling Our Debt gave the gift that keeps on giving (no, not fuzzy dice for the rear view mirror). She handed to bloggers everywhere some awesome tools to help manage their to do list, blogging tasks, advertisements, expenses and calendar.

I have about 30 posts by other authors I thought were fantastic this week, but in the interest of sprinkling a few highlights, that’ll be enough for now. Any more and it’ll be a list too long for you to enjoy.


We’re WAY Popular AND Modest


Thanks to everyone who tweeted our articles this week. I know I’m not great at the “hey, thanks for the RT!” posts. I don’t know how people find the time to do all the things they SHOULD do for others, get their blog written, hold down a job, and drink a case of beer a week. Sigh. Apparently people rearrange their priorities differently than I do….

Here are a few of the places that featured our writing or who talked about us fondly:

I guest posted at One Cent at a Time. It was about the rock band Rush and goal setting. Apparently that went over people’s head, because the post that I thought was my big winner of the week didn’t garner a ton of comment love. Apparently I’m not yet today’s Tom Sawyer…..

Cil Burke (clearly Dr. Dean’s better half) at the Millionaire Nurse Blog talked about how much fun we had playing board games at Fin Con in her post about surviving family functions. I was sure we were going to see liquid coming out of Len’s nose at one point. Can’t wait for next year to do it again. BTW, if someone wants a family game recommendation for the holidays, feel free to email me. I get tons of questions from family/friends this time of year about what the best option might be…..

Erin at The Dog Ate My Wallet and Kim at Eyes on the Dollar mentioned our post about dining and dashing at Pizza Hut. I love having friends who can reinforce my image as a reprobate…


In Closing


Thanks again for reading the blog this week! Next week we’ve got an awesome podcast episode on Monday, followed by posts Tuesday, Thursday and Friday.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: irrelevant stories, Meandering

  • « Previous Page
  • 1
  • …
  • 16
  • 17
  • 18
  • 19
  • 20
  • …
  • 32
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework