• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for money management

Blue Apron Company Profile and Review

March 17, 2017 by Emilie Burke 1 Comment

Blue Apron is a meal delivery service that delivers fresh ingredients for three or your ordered number of meals to your door. Their motto is “Food is better when you start from scratch.” I think we would all agree!

Food quality makes a huge difference in the meals we eat. While preparing food from scratch can sound appealing, it can be time consuming. Especially in households with two working members, it can seem almost impossible. Blue Apron fills a market need. For slightly more than regular groceries, as low as $8.57 per serving according to their website, they provide a premium meal experience at a less-than-premium price.

Blue Apron was founded in 2012. Since its founding, the company has raised roughly 194 million dollars, with its most recent rounding being a $135 million Series D raised in June 2015. Some estimates say the company has between 500 and 1000 employees with its 3 founders still holding C-level executive positions. They have been featured in The Wall Street Journal, Good Morning America, Tech Crunch, and The Washington Post, as well as many others.
blue apron company profile and review

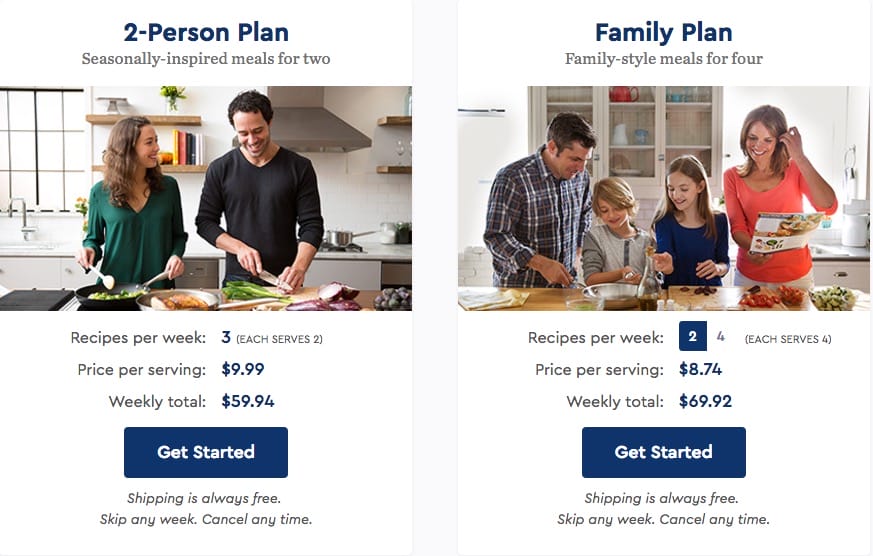
Blue Apron allows you to see what the price-per-serving cost of a meal is. This allows you to compare the price for Blue Apron to your groceries. Thing is, though, that Blue Apron can’t be compared to your groceries. You see, groceries are just food, but Blue Apron is a service!

You’re not only getting all the ingredients you need to make dinner, but you’re also getting the lack of a hassle- less groceries to worry about and less mind space to let dinner take up. Blue Apron, though, is not like going out to eat. You still have to do the cooking and the cleaning yourself.

The cost of Blue Apron reflects its middle ground between between going out to eat and just making a “regular” meal at home. The price, at $8.74 to $9.99 per meal, reflects that middle ground. It’s cheaper than $16/meal at some restaurants but nicer than the $4/meal you’re probably managing with your groceries when you make some dinner.
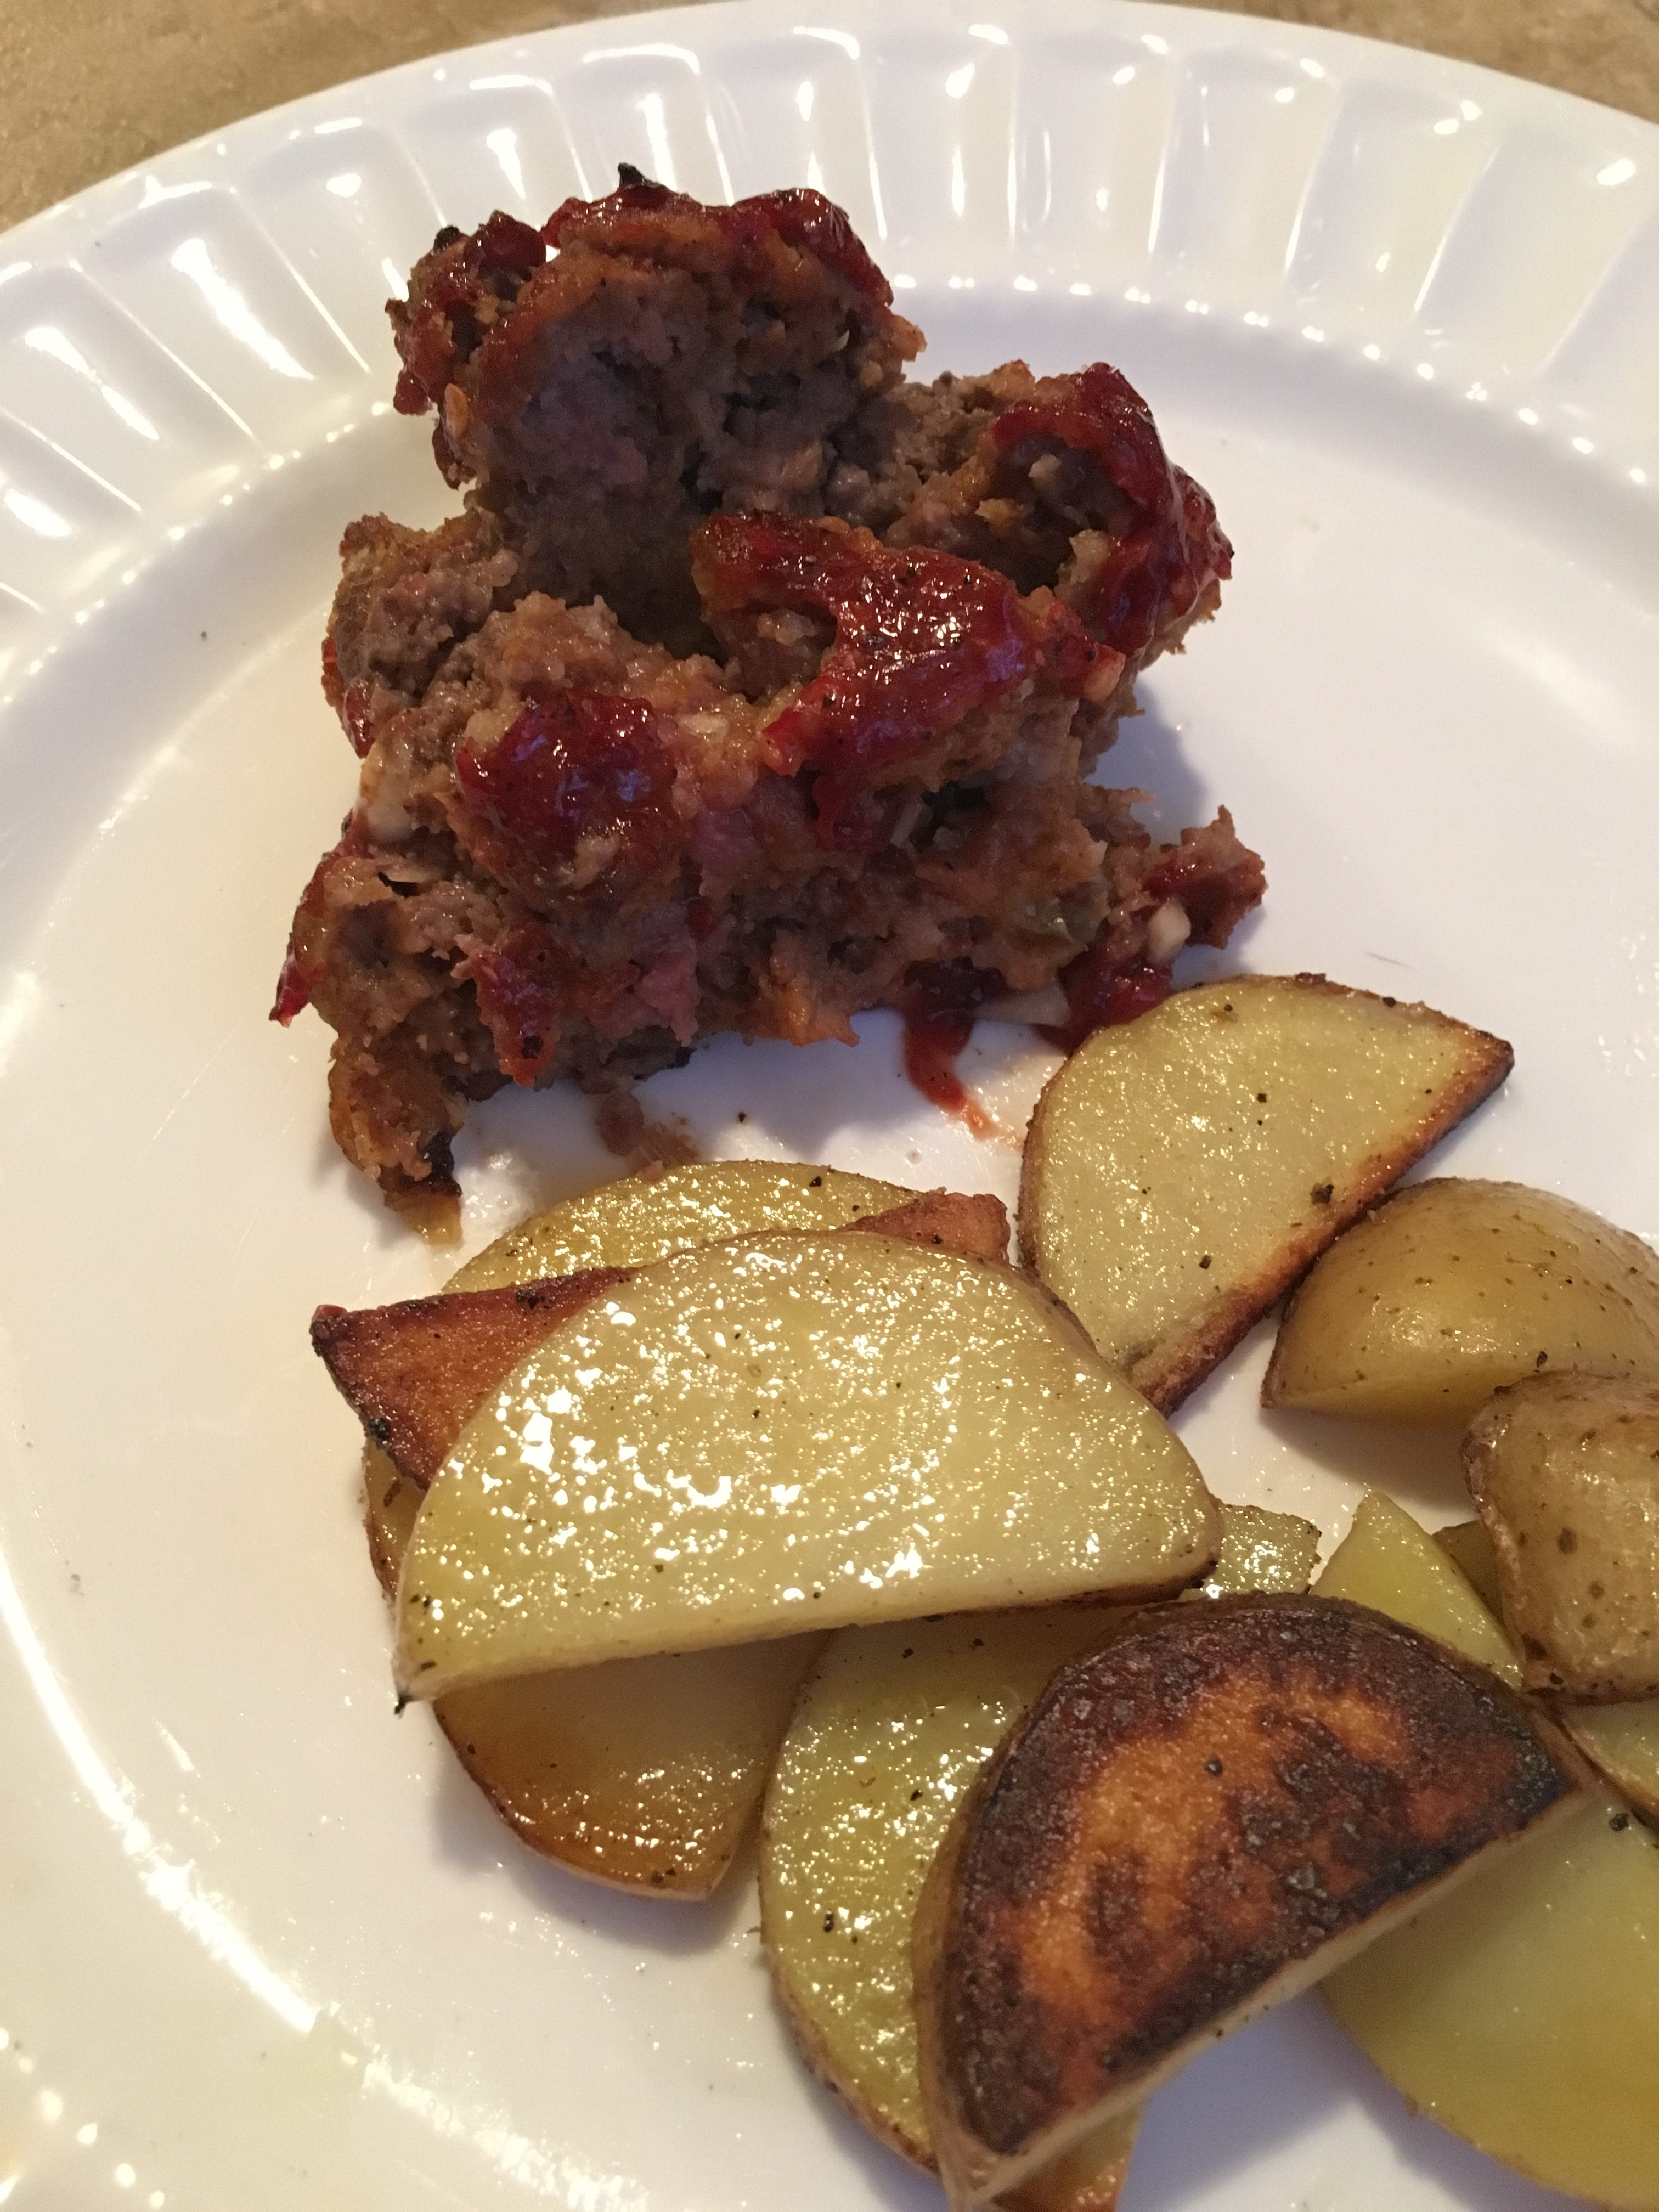
Plate of glazed meatloaf with roasted potato wedges

I got the chance to try Blue Apron myself! One of the three meals we tried was a Chipotle-Glazed Meatloaf with Crispy Potatoes. My significant other, Casey and I decided to make a Saturday date-night experience out of it. We were hoping it would fill that middle ground – a nice date night but one that didn’t require spending what going out to dinner. Casey enjoys cooking, but I’m not great at it. As a result, I don’t particularly enjoy it. Our Blue Apron date night let us spend time together in a great way, doing something Casey loved, and that supported our financial goals.

The following Sunday, Casey had to work the whole day. I prepared for us our second meal – Oaxaca Cheese and Plantain Tortas with Tangelo & Radish Salad. I was shocked by the prep time for this meal – nearly an hour – but it had less than 10 minutes of cook time. As a result, I was able to bring Casey a delicious meal and we got to share a not-so-picnic-lunch sitting in Casey’s office.

Blue Apron is a company growing in popularity, which is why you may have already heard of it. The company is set up for success and it has found product-market fix. You can see how it meets a need in real people’s lives. It meets a need in my life. That really says something.

You can try Blue Apron yourself and get $30 off your first order with this link.

Tell me more: Have you ever tried Blue Apron or another meal delivery service? 

I obtained free meals in exchange for reviewing Blue Apron. All thoughts and opinions are my own.

More Blue Apron reviews:

  • Cleverdude
  • Thousandaire
  • Budget and Invest
Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: money management

Financial Habits to Set Up in 2017

January 16, 2017 by Emilie Burke 2 Comments

2017 is a brand-new opportunity to meet goals and start habits that we want to prioritize over the span of the year. Resolutions are made every year to stop smoking, eat healthy, or go to the gym. Although physical resolutions are terrific, it is also important to place focus on our financial habits as we start the new year. What type of financial goals do we have for ourselves? What habits should we form now to help us meet those goals? Here are five financial habits that will be beneficial for 2017.

Pinterest graphic over a tablet calendar: "Financial Habits to Set Up in 2017"

Budgeting

Create weekly and monthly budgeting plans, and take time afterwards to review how well you are sticking to the budget. When you have a plan in place, it is much easier to save money and spend less. Reviewing how you are doing regularly will help you to evaluate where you are financially and what you should change.

Setting financial goals

Set some goals that are important to you and be vigilant in sticking to them. One goal may be to create an emergency savings fund of $2,000. Another may be to stay under budget for 6 months in a row. Whatever your goals are, write them down so that you can hold yourself accountable.

Avoiding debt

One of the greatest habits you can keep is to never create debt for yourself. This means always living beneath your means, and NEVER above. Can you create this habit for yourself for 2017? If so, you will be a happier you with healthier finances.

Contributing to retirement

Create a Roth or Traditional IRA and make it a habit each paycheck to contribute into the fund. It is never too early to start preparing for retirement. The sooner you start, the more money you will have saved up when the day comes.

Giving (some people may call this Tithing)

Make it a financial habit this year to give to others. This may come in the form of giving to a particular charity, tithing at church, or donating money to a cause you believe in. When we give to others, we are blessed in return. If allowed the opportunity, giving may do even more good in your life than you ever could have imagined.

Think of whatever habits are important to you financially this year and write them down! Writing down what we want is so important because only then can we continually hold ourselves accountable. Hang your list on the fridge or sit it by your bed. Every day make it a priority to continue these habits in your life.

If you think these 5 habits listed above could be beneficial to your own personal finances, then I encourage you to truly try to stick to them over the next 12 months. It is the small things that you do every day that bring about big change in your life. Healthy habits create healthy finances, and that’s the goal that we all should be aiming to reach. Good luck!

For more on forming habits, and ways to get rid of bad ones, check out these great articles.

5 Habits That Cost You Thousands
Increase Your Financial Stability by Taking Advantage of New Spending Habits
Sandy Smith Talks Gen Y Money Habits


Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: money management, Planning

Personal Finance Ratios: What You Need to Know

December 5, 2016 by Emilie Burke Leave a Comment

I strive for healthiness in all areas of my life: physically, relationally, and financially. The signs of physical health and healthy relationships are obvious, but what about financial health? How do you truly know if you are on the right track financially? Enter: personal finance ratios. These are calculations that allow you to determine where your financial weaknesses are; once you know your score, you can then make changes to be on the right track. Here are some of the most important personal finance ratios that everyone should know.

creating-luxury-home-budget

Total debt to income ratio: Ideally 0%, but no more than 35% of monthly (net) income. Banks use this ratio to determine someone’s default risk on loans, especially mortgages. This would include all debt, such as mortgages, student loans, credit car payments, car loans, and personal loans. Most financial professionals consider student loans and mortgages as “good” debt and stress lowering at least the consumer debt, if nothing else. 

Savings ratio: Between 10-20% of net income. This should be composed of your emergency fund, retirement fund, and college fund for children (if applicable.) Popular financial guru Dave Ramsey teaches that if you are working to pay off debt, you should have a basic emergency fund of $500-$1000  until you are debt-free, which I don’t necessarily agree with (I think it should be a bit higher.) He also teaches that you should wait to contribute to retirement once you are debt-free, which I also disagree with; if your employer offers a 401(k) match, to not contribute while you are paying off debt is like throwing away free money.

Housing ratio: around 25%-28% of net income. This would include not only rent/mortgage and utilities, but homeowners taxes, insurance, homeowners’ association fees, and money for ongoing home maintenance. If you live in an area with a higher cost of living, you may have to increase this amount slightly. 

Liquidity ratio: Cash divided by monthly expenses. This is just a fancy term for “emergency savings.” In the event of an emergency, such as a job loss, how many months would you be able to stay current on your bills? Ideally, you would have a minimum 3-6 months’ of expenses available in liquid accounts, although I am more comfortable with 9-12 months’ emergency savings.

Solvency ratio: Net worth divided by total assets.  Ideally your net worth would be 50% or more greater than your total assets. For someone who is just starting their career, this amount would be lower because most likely they have student loans and few assets, but as someone gets closer to retirement this amount should increase.

Being properly insurance is important because you never truly know what could happen in the future and want to be protected for anything that might happen.

Disability insurance amount: around 70% of your gross income.  If you were somehow unable to work, you would need a way to pay your bills.

Homeowners’ and auto insurance: the cost of replacing them and the belongings inside. If something happened to your house or vehicle, you would also need a way to purchase new ones. Ideally, this would be by insuring them for the cost it would take to replace them. At minimum, you should insure them for their fair market value.

Life insurance: This one is a bit more complicated, because it depends on your life situation. For example, I’m a single woman with no kids, so I don’t need as much life insurance as my friends with kids. If you’re debt-free with a large chunk of money in savings, you won’t need as much insurance as a person with a mortgage

Emilie Burke writer at the Free Financial Advisor
Emilie Burke

Emilie is a prolific blogger, and influencer inspiring millennial women to live financially, physically, and professionally fit lives. She writes about overcoming debt, while balancing trying to eat healthy, stay fit, and have a little fun along the way. She is a politics major turned data engineer who graduated from Princeton University in 2015.  She currently lives in North Carolina with her college sweetheart Casey who is currently stationed at Fort Bragg. She enjoys eating food, cuddling with her dog, and binge watching HGTV.
Filed Under: Insurance, money management

Yes, Someone Is Taking Your Money

June 27, 2016 by Joe Saul-Sehy Leave a Comment

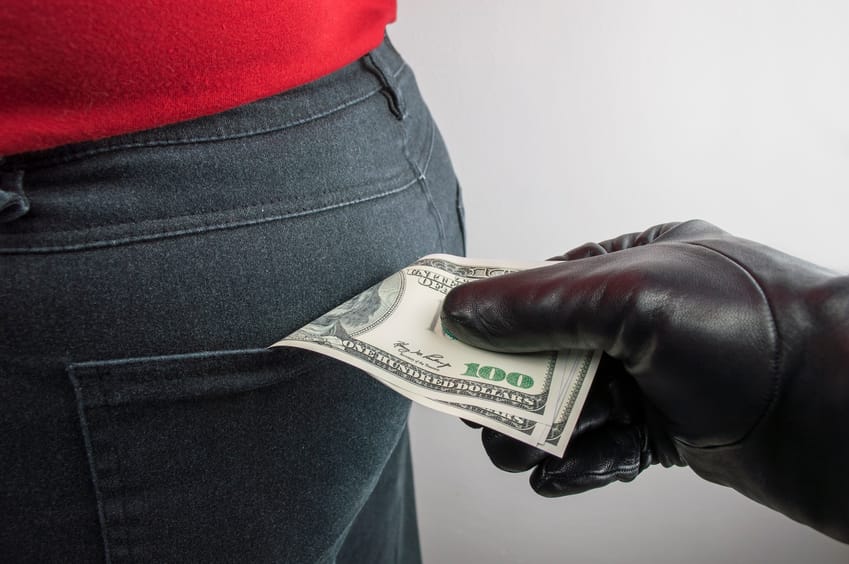
close up of a the hand of a thief stealing the dollars us to a woman

When we’re kids, the world of grown up finance seems distant and confusing. Bank accounts and mortgages are words we didn’t understand. Our only experience with money was the cash we carried to school, or the allowance our parents may have doled out to us every month or so. We might have lost a quarter while playing, or given up our lunch money to the bully at recess. Whatever it was, grown up money habits seemed safe and secure. We figured that once we got to be adults ourselves, we could lock away our savings in an impenetrable vault and live without worry that someone else might take it.

The thing is, though, people do take your money. Today more than ever, regular people are vulnerable to the predations of individuals and corporations who make it their business to steal or skim as many dollars as they can get access to. It’s not too different from the schoolyard bully situation, though today’s ripoff artists like to hide behind suits and expensive desks, or even cloak themselves in digital anonymity. For people looking to make their money go farther and last longer, it’s imperative to stop these characters before they start. It’s almost always easier to prevent theft than it is to recover funds. Here are some things to keep in mind.

  • PPI and Other Unwanted Subscriptions. PPI, or Payment Protection Insurance, is a fine financial product that was unwittingly foisted on many borrowers in England over the past couple of decades. It’s not that the insurance was bad. Most people just didn’t want it, and didn’t know that somewhere buried in their dozens of loan application documents was a contract they were signing for the coverage. Today there are many class action lawsuits in motion, and the PPI deadline is quickly approaching. There are examples of many similar ripoffs, but sometimes we’re our own worst enemies. Ever subscribed to entertainment or monthly shipments from Amazon or other providers? It’s easy to forget about these services and just let our funds slip away monthly.
  • Encryption and Anonymity. If I were to ask you which online passwords were the most important, which would you identify. No, not Facebook (though it’s not totally insignificant). No, not your HBO NOW account. Email and Banking? Yes! Totally! It’s getting easier than ever for hackers to crack weak passwords. When it comes to email, this is the gateway to all of the rest of the information available about you online. Most of us have our other passwords mentioned somewhere in our emails, so hackers often find financial passwords and move on from there. If they can get through a bank password without cracking your email, all the easier. Try Google 2-Step Authentication for your most important web accounts, and request that your institutions support 2-Step Authentication if they do not already.

It’s harder than ever to get through life without someone picking your pockets. In the digital world, it’s just like the old playground bully situation. Keep your stuff safe by paying attention and preparing for the worst. You might be able to keep your money to yourself.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, money management, Planning

What the recent stock market turmoil could mean for your finances?

February 24, 2016 by Joe Saul-Sehy Leave a Comment

The-Stock-Market-Plummets!-What-Should-I-Do-

What Could Happen To Your Finances?

The financial markets are highly unpredictable at the moment. It seems that every day there is a news story about another crash just around the corner. It can be scary for those who have their money tied up in the stock markets. Even those who do not have a lot of money in the markets may be worried, as the impact of changing stock market conditions can have an effect on their financial health as well.

It is always a possibility that the markets could take a sudden downturn and cause real problems. There is little that any one investor can do to stop the forces of the market. The markets simply react how they are going to react, and the rest of us have to do our best to ride the waves.

Current issues facing the market include issues in China as well as concerns about the Federal Reserve and what it will do with interest rates. The Federal Reserve raised interest rates a quarter of a percent at the very end of 2015. It was the bare minimum that they could raise them, and the first time that they had raised rates in nearly a decade. However, this did not stop the markets from reacting in a big way.

Many fear that the Federal Reserve raising interest rates could lead to a lot of devastating outcomes for the economy. They worry about a global economic slowdown, and about inflation taking off. However, as Reuters reports, there is probably little to be too concerned about in the immediate future.

There is every chance that the interest rate issue will be a non-factor for most. However, those looking into getting a personal loan of some kind may want to take note of these changes and how they could play a role in their life. Consider looking at a personal loan calculator for more information about what the interest rates could mean for how much you can borrow and what amount you will have to pay back.

The best thing that anyone can do when faced with stock market volatility is to wait things out and continue to invest in the markets the same as before. Most of the time volatile moves in one direction or the other are temporary and something that can be easy to overreact to if given the opportunity. All people should try the best that they can to ignore such movements and carry on as planned into the future.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, money management, successful investing

4 Life Hacks to Maintain Your Social Life While on a Budget

February 1, 2016 by Joe Saul-Sehy Leave a Comment

Friends Eating

One of the first things to go in serious debt elimination or cash saving budgets is entertainment. When you’re used to an active social life, this can become the most challenging part of the whole process. After all, just because you’re on a spending diet (or fast) doesn’t mean your friends are. They are used to you doing things with them—things that, more often than not, cost money—and they aren’t going to stop inviting you to fancy dinners just because you’ve announced your allegiance to Dave Ramsey.

So how do you maintain you’re social life while strapped for cash? Balancing a budget while keeping your social life alive is not only possible, it can be fun. Your budgeting days offer the opportunity to switch up the social routine by adding creative activities to the mix. Here are four hacks to stay social without spending an arm and a leg.

For the Drinkers

Host a beer tasting party. Not as stuffy or expensive as a wine tasting party, and slightly classier than bring-your-own-PBR Scrabble night, a DIY beer tasting party will thrill your social group. Invite beer-loving friends to bring a six-pack of a unique brew and hold blind tastings throughout the night with homemade score cards. Vote on first, second and third place.

For the educational-minded, have participants explain the history and science behind their beers. If you’re lucky, one of your friends will bring something fancy like Guinness’s new Nitro IPA—a smooth, creamy pale ale made with Guinness yeast—and teach you all about nitrogenated beers.

For the Foodies

Throw a recipe swap party. Improve your foodie game, save some cash and hang out with your friends in a fresh way all at the same time. It’s the same idea as a potluck except you choose a theme for the dishes and everyone walks away with a bunch of new recipes. Themes could be anything from appetizers to culturally inspired dishes. Along with their dish, each friend brings a stack of recipe cards to hand out. As the penny-pinching host, your goal is to keep your dish as simple as possible by making something from ingredients you already have, or mostly have, in the house.

For the Fashionistas

Organize a clothing trade. If fashion’s your jam, organize a clothing swap with your chic friends. Send out an Evite a month in advance, being sure to note a precise amount of items each person should bring to ensure quality, fair selections. Depending on how insane your friends are about free clothes, you might need to implement some additional rules such as a lottery system detailing the order in which people “shop” for clothes. This event is a two-birds-one-stone situation: an innovative way to spend time with friends and a fresh new wardrobe—for free.

For Anyone, Anytime:

Propose anything nature-oriented. If you’re worried about telling the whole world that you’re broke—don’t. Simply become the friend who has taken a sudden interest in Mother Nature. Most outdoor activities such as hiking, camping and biking are free or extremely affordable. Even getting together with a friend to walk the dogs through the park or a nature reserve can set the stage for quality time at the best price.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, money management, Planning

How to Get a Vehicle Loan: Tips for the Credit-Challenged Car Buyer

December 30, 2015 by Joe Saul-Sehy 4 Comments

Car Loan Paperwork


Buying a car is an exciting experience, one that everyone dreams about when they’re young. But when you’re an adult trying to buy a car with little to no credit, that experience is more like a nightmare. Although it may not seem like it is possible to get a good car loan with nonexistent credit, it is achievable if you ask the right questions and know where to look.

How long will the loan be active?

Before pursuing a loan, it is important to crunch some numbers and make some decisions. The first thing you should ask yourself is how much you can afford to pay each month and how long you are willing to pay it. You want to be sure the payments are reasonable and within your means. Don’t overestimate, but you want to pay as much as you can without setting yourself up to fail.

If you decide that a longer auto loan (more than six years) is best for you, know that your monthly payments will be lower, but you will end up paying more in interest over the life of the loan. Choosing a longer loan also means you run the risk of falling victim to depreciation. This means you could end up owing more on the car than it is worth, or the dreaded underwater scenario.

Do you have a co-signer?

If you alone do not look appealing on paper, adding a co-signer to the loan, like a spouse or parent, can make you look a lot more attractive to lenders. With a cosigner, the party lending the money has more options for recovery outside of the borrower. Essentially, if you have someone with good credit willing to vouch for you, you are more likely to drive away in a new or used car. However, you have now made that individual as equally responsible for the payments as you are.

Who will lend to you?

Don’t give up on a bank loan until you’ve actually tried. Know that you are more likely to be approved at an institution where you already have an account. If you are not approved the first time, it may be worth your time to wait and apply again a few months later, particularly if in those months you can demonstrate steady employment, change in income or steady credit payments.

If you have no luck at a corporate bank, try for pre-approval from a credit union. Credit unions are capable of making personalized decisions, especially if you bank there. A bonus is that credit unions tend to offer lower interest rates than banks, and they do not follow the bank’s tiered rate system, so your interest payments will be the same as any other credit union member’s, regardless of your credit score.

Another option is to go with a dealership that caters to customers with little to no credit, such as DriveTime. Its website states that it has approved over 2.5 million people and sold over 750,000 used vehicles to people with no or bad credit. It claims that it works with all credit types, so you are more likely to get approval.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: budget tips, Featured, money management, Planning

Get This, Not That: A Guide to Proper Father’s Day Gifting

June 18, 2015 by Joe Saul-Sehy Leave a Comment

While your dad might be one of the most important people in your life, he is undoubtedly also one of the hardest to buy for. When it comes to Father’s Day, the challenge of gifting your dad the quintessential gift can be a struggle. How do you get your dad something that conveys your appreciation, gratitude and love? More importantly, how do you get him something he will actually appreciate and hopefully not exchange? Here are some perfect gifts to make any dad feel like #1 on Father’s Day.

Techie Dad

If your first memories with your dad involve something like disassembling a radio just to see how it was put together, then your dad is probably techie. As with most tech fanatics, buying them a gift that will impress them is tough. They already own the computer, the SLR and every edition of PhotoShop. Due to their extreme devotion, they also own the brand new iPad, the MacBook Air and all the accoutrements. But, do they own the new Apple iWatch? While yes, this may be a little spendy (prices start at $399), you might consider amending the spend considering he put up with your teenage years. Just think about how incredible it will be to give your tech dad the one gift he wants, but won’t buy for himself. Yes, you’ll win best child of the year.

father and daughter in the park

Grill Master

If you dad is less of a tech fan and more a fan of being outdoors with his grill, impress him with the Napa Jack’s Barbeque Blast Gourmet Gift Basket from FTD. This awesome collection includes sauces, rubs and BBQ-themed snacks and is certain to dazzle anyone who enjoys spending their time perfecting their grilling technique. With its grill case and reasonable price, this is a gift that makes an impact without hurting your wallet.

Golf Dad

Golf dads might seem like they’re easy to buy for: a box of golf balls, a new polo, a round at his favorite course. But step out of the box this year and get dad something a bit more creative. Pro or not, everyone loses golf balls. And dad would probably appreciate some help finding them. These golf ball locating glasses from Hammacher Schlemmer are less than $40 and offer the tech advantage that will get your dad extra excited to hit the greens.

Beer Lover

What dad isn’t a fan of beer? While every dad has his own set of discerning tastes, it is easy to get a smile out of your beer-loving dad with a case of his favorite, or even a selection of new beers from around the world. This year, try the unexpected with a gift that keeps on giving. Gift your dad a subscription to a beer of the month club for only $40 a month, not only will dad get to try a new beer every month, he will feel the love all year long. If your dad is more the hands-on type, try a beer making kit (starting at $70) that will allow him to create his very own distinct brand of brew.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, money management

How to Finance Your First Car

March 2, 2015 by Joe Saul-Sehy 2 Comments

How To Finance Your First Car The Free Financial AdvisorAccording to NADA’s Annual Financial Profile of America’s Franchised New-Car Dealerships, dealerships sold or leased more than 15.5 million new cars and trucks in 2013. That accounts for a 7.5 percent increase from the year before. As car sales grow and everyone you know seems to be driving around the newest model, it’s tempting to jump in, buy it and speed off the lot with the wind in your hair. Despite the relative ease of purchasing a vehicle, it’s important to know your options, find the best financing available and negotiate a price in your favor. Here are some tips to get started.

Set a Budget

It’s impossible to know how much car you can afford without a budget in place. Make a monthly budget and see if you can stick to it for a few months before diving into an auto loan or car purchase. Make a list of your fixed expenses with a generous amount left over for emergencies and recreation. Use an app like Mint to help keep track of your budget and alert you on when you’re overspending on set categories. Remember it’s not enough to just plan for your auto loan. Consider the cost of your tag fees, car insurance, fuel, ongoing maintenance and extras like getting your car detailed or replacing a flat tire. As a rule of thumb, don’t devote more than 15 percent of your household income to transportation.

Know Your Credit Rating

Get a free credit report from a site like Annual Credit Report to check your rating. Your score can directly impact your interest rate on an auto loan. Your credit report can also alert you to any erroneous information, credit fraud or mistakes. Your rating is calculated with a combination of factors from your credit history, outstanding debt and payment history. Your score ranges from 350 to 800. The higher the score, the better loan you can probably get.

Shop Around for Funding

The upside to securing funding through an auto dealer is taking care of your loan and financing in one place. The downside, car dealers are often paid a commission for it. Instead, consider a dealer like DriveTime where sales advisers aren’t paid on commission, making it easier to trust their advice. They also offer a 30-day limited warranty, 5-day return guarantee and auto check history report on all used cars they sell.

Going with the car dealer’s loan offer or big bank isn’t the only way to secure a car loan. A community credit union generally offers lower rates and is more sympathetic to borrowers with lackluster credit history. Credit unions are known for offering more intimate customer service. Since they’re funded by their customers, they work for their members and aren’t motivated to sell you anything for their own financial gain. Profits from credit unions go back into their services and member offerings.

Negotiate the Price

Regardless of how you pay for your first car, remember the price is negotiable. Consumer Reports suggests purchasing a New Car Price Report to find out what the dealer paid and using it as a springboard for negotiation. Be warned, dealers like to lump everything together from financing to trade-in you might be offering. It can be difficult to figure out the numbers once it’s lumped together. Negotiate one thing at a time and stick to the monthly amount you want to pay. Start with your rock-bottom price and let the dealer work you up slowly to a reasonable price you can drive away with.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Debt Management, Featured, money management, Planning

Online Businesses: Lots and Lots of Benefits

October 18, 2014 by Joe Saul-Sehy 4 Comments

Today we’re pretty excited about owning online properties. I thought it’d be worthwhile to explore all of the benefits, especially for people reading this blog considering jumping into the fun!

Instead of hoping for a dream job and a big salary, owning your own online business can open many doors for you and buy you more benefits. On top of the perks many people talk about, like working from home and flexible hours, it also can keep costs down, helping you financially. Internet businesses normally operate at a fraction of the cost of brick and mortar stores. While with traditional businesses you would need to rent or purchase a building, Internet businesses are all online. Many programs such as Shopify simplify the process of starting up your business. It’s a smoother, easier glide path to profits. Compared to the thousands of dollars you’d spend in renting out space, you’d only have to dish out a couple hundred a month at most. Home Office Free Financial Advisor

General Benefits in Doing Business Online

  1. As popular website InternetBusinessJunkie mentions, you have the ability to reach more people if you do business online. Traditional businesses that have a set location don’t reach nearly as many countries as an online business does. Most online businesses have the ability to do national as well as international sales. This blog alone is read in over 35 different countries on a consistent basis!
  2. You can leverage the usage and growth of the internet. The best way to market your business is by networking and there are many free and low cost ways to market online.  Social media is a great free resource to do most of your networking.
  3. You are able to work wherever it’s convenient. As long as you have a laptop or tablet, you can work virtually anywhere with just a WiFi connection. This allows you to keep a more flexible schedule so you can work whenever you need to.
  4. No more commuting. This saves a ton of time and money, especially with gas prices these days. I wake up every day and walk over to my home office and begin working.
  5. Though you are responsible for your own taxes, as Smallbusiness mentions, this could work to your advantage. As long as you remember to, you are able to take out as much or as little as you please. By the end of the year, by paying in taxes as you go, you’re in control of how much you will receive back or if you’ll owe more all at the due date.
  6. It has been said that the Internet has created an economy all of its own. Since millions of people are doing business online, it is only a matter of time before many traditional businesses become a thing of the past. Dbwebdoctor states that in years to come, eCommerce will obtain its main growth from small and mid-sized businesses.

Be Set For Life Financially

Unlike traditional businesses, online businesses operate 24/7. This means that while you sleep, you’re still receiving orders from customers worldwide. This could take the guesswork out of figuring out the right hours to be open. Being the sole owner of your business also means that you set your own wages. You can determine what your products should be priced at instead of listening to the head of a corporate business telling you what to do.

Once you learn the ins and outs of selling online, you have what we refer to as “blue sky” potential. Sure, there are going to be some trial and error runs regarding what products you should sell, but once you know how to sell online, making money will follow. Building a business online also gives you the ability to work for something that you love to do, according to Lifehack. How many people out there can honestly say that they are working towards what they are passionate about and they love what they do?

Resources to help are also plentiful. There are pools of designers and programmers available to hire at places like eLance or Odesk, among others, if you need help building any aspect of your website. There are freelance writers who will write articles for your website and virtual assistants who can take care of tedious details concerning your business. This could take a lot of pressure off of your shoulders while you deal with your product line and customers. The Free Financial Advisor works with a programmer in Minnesota, a virtual assistant in Michigan and another in the Philippines, as an example.

If you have children and are currently paying for child care, this is another expense you can think about canceling. Since you have the ability to work from home, you won’t have the need to spend hundreds of dollars a week for a babysitter. Though you may want to hire a babysitter once or twice a week if it becomes too much of a distraction juggling all of your responsibilities, you won’t pay nearly as much as if you went back to a full time daycare.

Between saving money on everyday expenses and making money at your own leisure, if you are dedicated to your business, you will be able to make it work. There are many resources online that can help you through your journey to owning your own business.

Photo: Lisa Risager

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Featured, money management, passive income, Productivity

  • « Previous Page
  • 1
  • …
  • 13
  • 14
  • 15
  • 16
  • 17
  • …
  • 20
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework