• Home
  • About Us
  • Getting Finances Done
    • Hiring Advisors
    • Debt Management
    • Spending Plan
  • Insurance
    • Life Insurance
    • Health Insurance
    • Disability Insurance
    • Homeowners/Renters Insurance
  • Contact Us
  • Our Editorial Commitment

The Free Financial Advisor

You are here: Home / Archives for successful investing

Graduation Gifts: What Should You Do With Your Money?

June 14, 2012 by The Other Guy 21 Comments

‘Tis the Season!

Well, not that season, but another highly anticipated one: graduation season.  Hundreds of thousands of college and high school graduates are donning caps and gowns,  shaking hands, having parties, and most likely cashing checks.  The real question is what to do with all of this money?

Let’s break our discussion into two categories: high school graduates and college graduates.

High School Graduates

We’ve talked about it periodically: most kids aren’t taught anything about how to handle money and for some, graduation gifts can be their first experience with large amounts of cash. If there’s not an exact plan, it can blow away faster than the autumn leaves.  This is job number one for parents: sit down with your kids and discuss what the plan is with the graduation money.  Here are the top 3 things high school graduates can and should do before cashing a single check.

English: PJPII graduates entering local church...
High school graduates entering local church for graduation mass, May 2009 (Photo credit: Wikipedia)


  1. Establish the maximum dollar amount of your graduation gifts that you’ll allow yourself (or your kid) to spend on fun.  I don’t have any problem with high school graduates blowing a certain amount.  I mean, it is a joyous occasion and high school graduations should have a certain amount of indulgence.  But, just like anything finance related, you have to go in with the end in mind.  Failing to plan is planning to fail.
  2. Decide what’s going to be set aside to be spent during the first semester of college.  Assuming you’re heading to college in the fall, no matter what you think you’ll need from graduation gifts, you’ll want more.  Accept and embrace the reality: college will cost more than you think.  If you can set aside a couple hundred dollars today for those rainy October weekends far from home, you’ll feel a lot less guilty about skipping the meal plan and ordering a pizza for your roommates.
  3. Take at least 1/3 and either invest it or give it away.  Those two options sound like opposites, but they require similar mental acuity.  We only give things away when we have an abundance mentality – we only invest if we have a strong faith in the future.  Take one or two hours and pick a solid blue chip company, set up an online brokerage account, buy some stock and don’t touch it for 30 years.  You’ll thank me later.  Oh, and don’t forget to reinvest all your dividends from your graduation gifts! You’ll want those growing, too!

Don’t let this great opportunity for teaching kids about money slip by.  There are only a few “found money” times throughout one’s life.  Use graduation gifts wisely.  Any high school graduate should be able to take this money and use it to get ahead in life.

Next week we’ll talk about what college graduates should do with their “found” money…stay tuned!


Enhanced by Zemanta

Filed Under: money management, successful investing Tagged With: Education, Gift, Graduation, Higher education

How Did You Golf Today? Ask Me About My Portfolio….

June 6, 2012 by The Other Guy 14 Comments

If you’re a subscriber to our podcast, then you know one of the things that I really enjoy is golfing – so it’s not uncommon for people to ask (even if they’re somewhat kidding) “So, how did you golf today?”  (Truth be told – pretty bad.  I’m usually a mid-80’s golfer, but today I shot a 93.  Boo.)

To me, answering the “how’d you golf today” is the same as “What did the market do today?”  I don’t like answering either.  Trust me – when I golf well, or if the market did exceptionally well today, I’ll let you know.

Golfing and investing are very similar; they both require similar skill sets and disciplines.  Last week  discussed how you have personal responsibility with your investing plan

– today let’s talk about what to do when you hit a wayward tee shot.

Sometimes even with the best swing, the ball just slices ever-so-gently into the rough (or as was my case today, the bunker).  How do you respond?  Well, there are two ways: first, you can throw your club, swear at the wind (or the tee box, or your teammate, or whatever) or you can focus on what you need to do to get the ball back in play.


One of the first things I learned about golf, after I gave up the swearing and became  semi-serious about it, was to always try to get the ball back in play.  If you’re in the bunker, goal #1 is to not have another bunker shot.  If you’re in the rough, goal #1 is to get it out of the rough.
Unless you’re pro golfer Bubba Watson and can snap-hook a 7 iron from 185 yards in a playoff hole in the Masters, goal #1 is just to get the ball back in play.Investing and financial planning follow the same logic.Sometimes you hit a crappy tee shot (read: make a bad initial investment, have some external


force impact you financially, etc.) and you can respond only one of two ways:  you can throw your statement, complain about how your broker screwed you, whine about how the dude on CNBC lied, or:

you can get back in play.

Sometimes that means you have to punch out of the rough under a tree branch; sometimes you have to layup to the 100 yard marker; either way, don’t get upset – just get back in play.

Tiger Woods hitting a golf shot on the fairwayWhen you make a poor investment decision that means:

1) Don’t worry first about assigning blame. Worry about correcting the problem.

2) Stay calm. Getting upset isn’t going to help you create better returns later.

3) Once you’ve regrouped, THEN determine what went wrong. Was your broker the problem? Did you not analyze the investment correctly?

You’ll invest much better following these simple steps that I learned from playing golf.

Filed Under: Meandering, successful investing

A Chart that Frightens Me: Investing 101

June 5, 2012 by Joe Saul-Sehy 20 Comments

In the past several weeks, I’ve ground my axe on charts that are either misleading or actually say nothing.

Today, let’s counterpoint: I’ll show you a chart that makes sense to me AND fills me with more dread than seeing Aunt Ernestine in a swim suit.

…a rather unflattering swim suit.

I found this chart at FRED, an acronym for Federal Reserve Economic Data. This website is chock-full of charts and graphs direct from the government and financial institutions. And, as a bonus, they’re usually easy to understand.

Bonus!

Here’s the chart I’d like to focus on today, class:

Fred 10 yr 1 1-4 percent treasury inflation-indexed note, due 7 15 2020


So, if you aren’t familiar with Treasury Inflation-Indexed Notes, don’t start nodding off on me! I’ll have to send Aunt Ernestine over to sit on your lap.

That woke you up.

Let’s explain what the $%!@ we’re looking at here.

As you can see on the header, this chart shows the yield-to-maturity on a 10-Year Treasury Inflation-Indexed Note.


What’s a “Treasury”?


Investments that are simply referred to as a Treasury in the U.S. are products of the U.S. Government. They’re sold at an auction. The amount of the note is fixed (you buy in $100 increments), but the interest rate is what they bid on. If nobody bids, the government will have to pay a high return to lure investors. IF lots of people bid, the government is able to sell the debt for a lower price. Initially, this debt was priced at 1-1/4%. That’s a nice win for the U.S. Government.

As an example, if you have great credit, you do this with credit cards. Instead of jumping on the first credit card offer, you examine the interest rate. If it’s higher than you want to pay, you keep searching. Essentially, you’re pitting “investors” (lenders) against each other for the pleasure of holding your debt.

What’s a Note?


A note is a ten year bond. Once the bond is issued (this one was issued in July of 2010), it’s paid off ten years later.

Do you have to wait ten years to sell your bond? No. You’re allowed to sell early, but you’ll do it on the open market.

The open market conditions produced this graph.


What Does the Graph Show?


This graph DOESN’T show you the price of the ten year bond. Instead, it cuts to the chase. If the bond is sold initially for $100 (called the Par Value), and an investor will give you $105 for it, he should already know that he’s only going to receive $100 when the maturity date comes. Therefore, it’s a simple computation: if you over or underpay, what is the true interest rate you’ll receive?

This chart shows the true rate if you purchased this 10 year note today.

In short: the price is so high you’re guaranteed to lose money.

Ouch.


Why is this Frightening?


If investors are comfortable loaning money to the government, knowing that they’ll lose money, this means that other places to invest money are even uglier.

In short, we can discern:

– There is much constenation about the financial markets now

– Lots of investors feel comfortable losing a little money with the U.S. government

From that I infer that investors think they’ll lose more elsewhere.


Is This An Opportunity?


Clearly, there is less opportunity in Treasury Inflation-Indexed Notes than there is with Aunt Ernestine. However, some investors may think that this means that the panic has gotten so high that there are obvious opportunities elsewhere.

Maybe.

Remember that the majority of traders have more money than you and I. Professional traders work from platforms that spend more money on research than we spend on our homes. If you’re looking for opportunity, it isn’t apparent in this particular graph. You’ll need to look further.


Where Do You Look Next?


This chart leads me to want to see past correlations between the 10 Year Treasury Inflation-Indexed Note market and other financial markets. By viewing these, I might be able to better discern if this is simply panic or something bigger.

More on that another day.

For today, know this:

– FRED is a good place to find charts and graphs

– Treasury note graphs can give you clues about the market overall

– You can lose money in government bonds if you buy them on the open market


Is there anything I missed here? Let’s chat about this market and investments in the comments, minions.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: investing news, investment websites, successful investing

Facebook and Morgan Stanley: Who is To Blame?

May 30, 2012 by The Other Guy 15 Comments

Whose responsibility is it when your investment in Facebook or Morgan Stanley declines in value? The company? A broker?

Certainly you’re not to blame.

The current proliferation of lawsuits against these companies makes me ask a straightforward question. Should there be lawsuits against Facebook and Morgan Stanley? (See these articles for more information if you don’t know what I’m talking about: Forbes: Facebook Lawsuits Piling Up.)

I’m reminded of society’s lack of personal responsibility each and every time I drive up the highway to see my mom.  I haven’t added all the advertisements up, but there is a certain personal injury lawyer in our town who advertises everywhere.  I don’t know this lawyer intimately, but my wife works in the same office building and sees the people who come in and out of the front door.  There are all sorts of people trying to sue for anything under the sun.  Instead of trying to take over the world, they’ll just take it from someone else, because somehow, they’re “owed” something.

One of my favorite books is The Road Less Traveled by M. Scott Peck, M.D.  That book contains my favorite quote from any book:

We cannot solve life’s problems except by solving them. This statement may seem idiotically tautological or self-evident, yet it is seemingly beyond the comprehension of much of the human race. This is because we must accept responsibility for a problem before we can solve it. We cannot solve a problem by saying “It’s not my problem.” We cannot solve a problem by hoping that someone else will solve it for us. I can solve a problem only when I say “This is my problem and it’s up to me to solve it.”  But many, so many, seek to avoid the pain of their problems by saying to themselves: “This problem was caused me by other people, or social circumstances beyond my control, and therefore it is up to other people or society to solve this problem for me. It is not really my personal problem.”

This is as true in the investment world as anywhere. As an investor, you must accept responsibility for your own investing decisions.  You cannot blame others for your decisions (or indecisions).  You won’t help your cause with a “I’m mad I made a bad decision in investing so I wanna sue everyone” mentality.  Recent lawsuits against Facebook and Morgan Stanley make me crazy – I don’t believe for a second that if some magical prospectus would’ve fallen from the sky that all these people wouldn’t have bought Facebook stock.  There’s all this talk about how Morgan Stanley screwed everyone and how Facebook lied — why didn’t these people do their own research?  Take some personal responsibility!  I’m pretty sure that had Facebook stock gone from $38 to $75 in one day, Morgan Stanley would not have called all the new shareholders and said “Oops, we priced this incorrectly so we need to sue you to find a more correct price.”

As an investor, you and you alone are responsible for the actions and outcomes of your investing decisions.  Whether you have an advisor, a consultant, or are a DIY’er, remember one thing: it’s your money.

Be accountable for it.

Enhanced by Zemanta

Filed Under: Meandering, smack down!, successful investing Tagged With: Business, Facebook, Initial public offering, investing, M. Scott Peck, Morgan Stanley, personal accountability, Wall Street

Beware Charts, Graphs and Snake Oil

May 24, 2012 by Joe Saul-Sehy 15 Comments

I did away with my Boner of the Week! series that called out stupidity in financial media and blogs because I didn’t want to be that guy. Well, at least not be that guy not every week.

But this site is called the Free Financial Advisor for a reason. My task is to show people the difference between the truth and lunacy; to dole out useful tips that you can apply, sprinkled with my own quirky sense of humor.

Buy the doughnut, the frosting comes free. Bargain!

What I also drag along is a HUGE sense of anger when I see absolute baloney (polite terminology) on the internets.

I fought it as an advisor, and I’ll fight it here for you.

So, this week I’m going to un-bury the Boner of the Week! segment, along with the prerequisite, er, uncomfortable picture. Because I’m too lazy to find a new one, you’re treated to my favorite from the old series.

You’re welcome.

Let’s rant:


A Tip For New Investors:


If someone shows off a chart with a couple squiggly lines and points at them BUT REFUSES TO TELL YOU WHAT THEY MEAN it isn’t “analysis.”

It’s smoke and mirrors.

That’s why I like the DQYDJ blog and ws fired up when PK agreed to join our little podcast. He presents a chart or concept and then explains it. I’m a little smarter for visiting DQYDJ. Check out How Do You Know You’re Ready For Active Investing? Sure, I get PK’s returns, but I also get books to read, a chart on his personal progress and the story of how he began. Good story, good tips, good times.

Onboard?

Don’t try to just show me a chart and tell me “I predicted the financial markets would decline, and see, I’m right.” No reference to how the chart works. No rationale behind the prediction. Just “I’m right. Deal with it.”

Even if the chart is flippin’ brilliant, do you treat financial sites like the circus? Do you come here to see my dogs and ponies? My smoke AND mirrors? Do you want me to flash you a quick glimpse of my 12 inch wealth of knowledge so you can swoon over it?

Hell, no!

Like you, I visit sites for tips and tricks THAT I CAN USE. I don’t want to be shown stuff that I don’t understand.

If you hand me a shovel and I don’t know how to dig, all you gave me was a stick with a funny metal end.

Our “Boner of the Week!” target post (which I no longer point to directly, because that’s not the point of the piece….the point is to help you make better, more informed decisions. If you visited this bloggers site this week, I’ll apologize on his behalf), told us this week that “Mr. Brilliant” called the exact day the market was going to decline. He then advised us to stay out of stocks because it’s a bad, bad time for the market which will correct to (AND THEN HE BESTOWED UPON US THE EXACT RANGE!!!!).

Someone alert Jim Cramer. There’s a new sheriff in town.

Why the hell isn’t this guy working for a huge Wall Street firm or being paid the big bucks by wealthy investors who eat these gurus up? I used to ask my clients this question when they’d bring in what I’d call “miracle fliers” from their mailbox. Some dude telling them that he has all the answers.

I was a good financial advisor. I knew one thing: I didn’t have all the answers. Ta-Da!!!

Oh, my friends, that alone wouldn’t raise my ire. Ready for the next one?

Then he tells us to subscribe so we can find out what stocks we should buy when the time is right.

Thank you, your lordship Mr. Merlin soothsayer.

I don’t want a magical list of stocks. IF I did, I wouldn’t be looking for them on your free internet site.

Here’s what I want: tell me the criteria you used and I want to be taught to use it.

CD box set cover: How to Sell the Whole F#@!ing Universe to Everybody... Once and For All!


What I’m Railing Against


Did the dude call the market?

Yup. It appears he did.

Could he know how market conditions work?

Yup, he maybe can.

Are you just whining, Joe?

No.

I want this dude to tell me why, not what! A site like this is dangerous because you become dependent on the author. What happens if Mr. Brilliant has a Philly cheesesteak sandwich that doesn’t agree with him tomorrow and his indigestion decides that you should go 100 percent into Zynga stock? Or he tells you that the end of the world is coming and you should sell everything? Would you just follow like a lemming off the cliff?

  • Don’t follow someone blindly.
  • Learn to do your homework.

I naturally mistrust when ANYONE tells me they can call the market (after 16 years as a financial pro I saw professional gurus get beaten down by the financial markets time and time again).

One of my favorite stock trading books is called Trading Rules: Strategies for Success’ target=_blank>Trading Rules, by William F. Eng. The basic tenant of the book is that you do yourself a huge favor when you quit pretending you know anything about the financial markets. Once you realize that it’s a freakin’ scary-ass place, you’ll start protecting yourself and making money.

One of Mr. Eng’s fundamental rules: Tips Don’t Make You Money (Rule 7).

William F. Eng is a wealthy trader. I understand his background. I know nothing about wonderboy Mr. “I called it” dude.

Set stop losses. Learn how fundamental analysis works. Explore technical analysis.

But don’t let someone tell you when it’s the time to buy and the time to sell JUST BECAUSE THEY TOLD YOU SO!

They won’t lose the money, you will. And then you’ll be cursing the blogger, who won’t hear you over the dance music he’s playing for the rest of the suckers who hang on every word he says.

Rant over.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: Meandering, risk management, smack down!, successful investing

High Yield vs. Other Investing Categories in Pretty Pictures

May 16, 2012 by Joe Saul-Sehy 14 Comments

When words don’t work, I’ll emulate my buddy PK at the DQYDJ blog and resort to graphics when explaining your investing options. Since I can’t personally be bothered to create any type of creative chart, I’ll instead use a graph that I  received from a friend.

Before we peruse this particular investing chart, I should introduce it, like a big star explains the movie clip:

People worry often about risk when investing. You should. It doesn’t make sense to risk your portfolio without knowing what type of return you’ll receive.

As an example, one of the riskiest investment classes is art. I know and you know that your dogs-playing-poker is probably a timeless classic, but beauty is definitely in the eye of the beholder on that one. Unfortunately, if you paid $10k for your Velvet-Elvis-and-the-Eagle rug, that’s probably considered a capital loss.

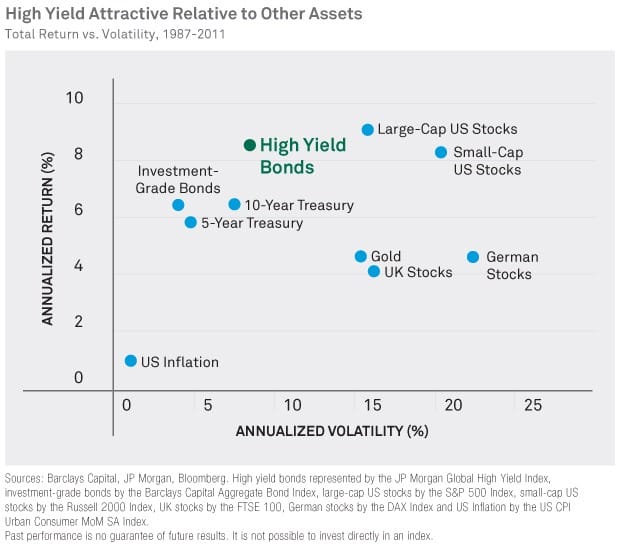
Here is the risk/reward profile of high yield vs. other asset classes:


Chart of Risk and Return


People are generally shocked when they see the risk/reward profile of high yield bonds. Is it true that JUNK BONDS are significantly less volatile than large-cap stocks?

Yup.

High yield bonds aren’t much more volatile than 10-year treasuries (which, ironically, have been more volatile than investment-grade bonds)?

Yup again. I knew people who came to this website are flippin’ brilliant.

Maybe now is a good time to review my posts last week on the topic of high yield bonds:

Off topic: Check out German stocks. Lots of volatility, plus those people wear black socks with sandals. I don’t know what those two points put together says, but it sure feels awkward.


How about you? Does this chart surprise you? Can you see my love affair with high yield? Make you laugh? Improve your outlook on life?

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: investment types, successful investing Tagged With: Asset, bonds, bonds vs. stock, Dogs Playing Poker, high yield, high yield risk reward, High-yield debt, Market capitalization, Velvet-Elvis

JP Morgan: Opportunity or Trap for an Investor?

May 15, 2012 by Joe Saul-Sehy 15 Comments

While gold seekers in the stock market chase the Facebook IPO like NASCAR fans after a Dale Earnhardt Jr. autograph, my attention is leveled at JP Morgan Chase. I’m wondering if their recent stock hiccup is an isolated mistake or the beginning of a larger crisis.

This isn’t how most new investors act. Most hear bad news and run the other way.

You can profit from investing well-placed dollars into investments while others panic. In fact, I think it’s fun to prey on investors who throw logic out the window and panic.


In 2004, when investors panicked and sold investments around the Indian ocean after the tsunami, I snatched up iShare Singapore stock exchange shares (ticker: EWS). This was an easy decision: while many of their trading partners were hit hard, Singapore was not. There was bound to be a ton of shipping to rebuild the region, all to Singapore’s gain.


While not a homerun, the stock was an easy win. I’m not looking for huge gains….I’ll take good gains while minimizing my risk.


I didn’t want to prey on the awful event….I was very happy to prey on the morons who thought this was a good time to sell their investments in Singapore. Do your homework before panicking.

The market is usually a fairly efficient beast (I don’t want to have the “efficient market” argument in the comments, so please save them for another site), but during times of panic there’s money to make.

So, after JP Morgan Chase announced a $2 Billion dollar loss last week, hopefully you  also thought: “this looks like an opportunity.”

Not so fast, cowboy.

Before you invest money into ANY struggling company, you should understand the risks of this strategy. I do well because I pick my stock market spots carefully.

It looks so juicy, though!


Agreed.

On May 1, JPMorgan (JPM) was trading at $43.79. Yesterday JPM closed at $35.79. That’s a loss of over 18%.

If your thoughts immediately turn to “too big to fail,” you might be right (jokesters are out in droves with “too big to regulate” and others today).

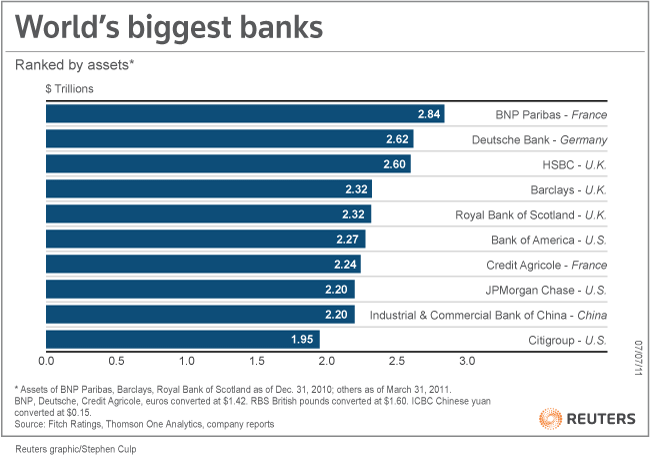
As of July of 2011, JP Morgan was the eighth largest bank in the world, according to Reuters:


World's Biggest Banks - Reuters


By many accounts, while $2 billion is large to you and I, JPM manages a stable of $2.2 trillion in assets and should be able to weather this storm.

Still, we need to do our homework before investing.


Follow These Steps


1) Understand the company, not just the situation. There will be news around JP Morgan in the next few weeks that I can almost guarantee will affect the stock price. Even if none occurs, it’s better to plan for news. Because you don’t know what the headlines will read tomorrow, have a solid a feel for the operation and scope of your target company to process how the news affects your position in the stock market.

Buying distressed companies isn’t about the initial purchase. You have to follow and respond to breaking news closely.

2) Evaluate the Risks

  • JPM could have severe penalties applied.
  • JPM may have broken the law.
  • Management may be forced to change (the Chief Investment Officer, Ina Drew, left yesterday).
  • Negative publicity could affect the performance of other divisions of the operation.

3) Sector analysis

You might find your dream company with an “oops” situation that’s easily fixable is in a nightmare sector where events are working against you. Any chance of a stock rebound is wiped out by prevailing conditions.

I thought this might be the case in early 2006. Ford pre-announced during their earnings report earlier in the week that they were going to unveil a major restructuring plan on January 23. Although layoffs aren’t a good sign over the long term, these quickly buoy the bottom line, giving hope to investors that the company will turn the corner. On the surface, this looked like a great event to invest in; a sure win.

There were significant downsides in the sector: at this time, the Detroit auto scene was in shambles. Auto supplier Delphi had declared bankruptcy only months earlier. Chrysler and GM were experiencing pain of their own. Did I really want to bet on a nice uptick in Ford stock over the short term when other auto news might sink my gains?

I explored the situation further. GM had already announced for the quarter a few days earlier. Chrysler had already experienced their blood letting, so I didn’t expect any short term news to disrupt what was looking like a quick trade.

In the final analysis, I made the trade, but because of the larger situation in the sector, I committed a much smaller portion of the portfolio than I’d originally intended. Plus, I became adamant that I’d set a quick turnaround on the stock. I’m usually a long term investor, but in this case, I was looking for a quick win.

I got it.

The morning of January 23, Ford announced a 30,000 job cut and the details of the restructuring. It was as large as expected. A stock that was trading at $7.90 the Monday before closed at $8.65 on the 25th. I was out, though, selling at $8.60. Nearly 10% in a few days was enough risk for me. This was one of only two or three times I’ve ever made a quick trade, and I don’t normally recommend it.

JP Morgan isn’t the same situation, but hopefully you understand my point: by analyzing other auto companies, I minimized the chances that news from them would work against me.

In the case of JPM, you’ll need to consider that state of banking. Is there any pending legislation that may affect performance? Is 2008 or a similar melt down in this sector or the wider stock market likely to occur?

4) Set defenses in place. Beginning investors should always work with a defensive strategy. I prefer a stop loss, but you may have other ways to reduce risk, such as the use of options. If you use a stop loss, you’ll want to give it a wide berth off the current price. Any stop loss placed within a few percentage points of the current trading level is bound to trigger due to the increased volatility of the stock.


magnifying glass II


Widen Your Lens


Because of a high credit rating, JP Morgan debt has been expensive, usually trading well above par value. If you feel JPM isn’t going to go bankrupt, then maybe looking for panic in the debt rather than the stock market is a better option. Here are some reasons I like trading debt instead of equity:

  • I know my end game (I’m guaranteed par value on the security at maturity as long as they don’t go belly up).
  • I can still sell on the open market.
  • I’ll receive dividends along the way, reducing my risk.

One such beast is a preferred stock. We’ll address preferreds in detail another day, but although they carry the name “stock,” a preferred acts much more like a bond.

A few questions to ask before investing in bonds or preferred stock:

  • What is par value. Many JP Morgan preferreds are trading at $25.50 or higher currently, while par value is $25 for preferreds (it’s $100 on most bonds).
  • What is the dividend? The stated dividend is based on the par value, so your dividend will vary from that stated on the preferred. If you’re using a website such as Bigcharts.com or Yahoo! Finance to evaluate the stock chart, the listed dividend is in fact the dividend you’ll receive at the current price.

Don’t just explore debt. Think further afield. Are there other companies that stand to win big because of JP Morgan’s stumble? Research these firms thoroughly before investing.


Final Thoughts


I’m not sure if I’m going to invest in JP Morgan. I’m more likely to buy here than in Facebook, a company with lots of hype and whose upside I don’t understand (most of my friends are tiring of Facebook, never a good sign for any product).

If you take anything from this discussion, I hope it’s the following:

– Think contrarian. When everyone else is running, ask “is this an opportunity?”

– Don’t buy immediately based on your contrarian “gut” reaction. Like buying a house or car, perform due diligence. Explore the company, the situation and the sector. Widen your lens to see if there are additional plays (such as debt or a competing company) that might make sense.

If this sounds like a lot of work, or individual stocks don’t fit your risk profile, stick with ETFs and mutual funds. Your chances of getting burned in your investment strategy is significantly reduced by staying diversified. Even if you do invest, don’t take large chances on “rebound” companies with significant portions of your portfolio.

Let’s pretend you were me: would you buy JP Morgan with a few “at risk” dollars? Are you jumping on this stock?


Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: investing news, successful investing Tagged With: Chief investment officer, distressed investing, Ina Drew, Jamie Dimon, JPM, JPMorgan Chase, Singapore

The Waiting Is The Hardest Part

May 9, 2012 by Joe Saul-Sehy 17 Comments

I called my mother in law to check in yesterday.

I get worried about people after a loved one dies, but especially I’m concerned about her, right now. My in-laws were a close couple. She’d always yell, “Dave!” at him for one reason or another, but there was a camaraderie in her admonishments.

She enjoyed admonishing him and I could have swore he enjoyed being admonished.

There’s no way I can imagine what’s going on in someone’s head the day after their spouse passes away. It’s beyond imagination.

Still, my call to her was shocking.

I was surprised to find that she’d already called her financial advisor about moving money around and scheduled a meeting with the Medicare people about Papa Dave’s hospital bills.

Wow.

A piece of this I understand:

– The need to keep moving.

– The desire to run.

– The longing to make things feel better and to grab control.

I understand that, and it makes me want to give my mother-in-law a big fat hug today. All the running in the world won’t make the pain go away. There isn’t a hug big enough to swallow all those years of being together.

That’s why it’s a difficult pill to swallow when I tell you what I told her: Be still. Wait.

When any major life event occurs, the worst decision is to change your financial picture.

My best advice? Do nothing. Zip. Zero. Nada.

Too many times I’ve had clients come in after a spouse passes away and they want to make changes. Not little changes, mind you, but major, life changing moves. Let’s guarantee my money won’t run out. I want to take a trip around the world. It’s time to sell the house and move closer to my kids.

These are all valid thoughts, but not for today. Today’s a time to work on other areas.

– Go for a walk.

– Sign up for cooking classes.

– Learn a new language.

– Dive into a hobby.

All of these are positive life experiences that you can bow out of later without major repercussions. If you decide to sell your house and move, what if you don’t like the new place? If you change investments and the market tumbles, how will you respond?

Too many times I’ve witnessed people who’ve made life changing decisions without a clear head, only to regret all the moves later.

Often this regret, coupled with the sorrow of the original loss, is crippling.

How long do you wait?

I don’t know. 16 years of advising people who watched spouses, parents and children die still wasn’t enough for me to help you there. I can say this: Everyone was different. I will tell you that both my client and I knew when it was time to start moving. I’m sure you’ll know, too.

So, maybe Tom Petty was talking about a completely different topic, but he’s still right: The Waiting is the Hardest Part, but it’s the most important. Wait.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: money management, successful investing

How I Chose My High Yield Bond Fund

May 1, 2012 by Joe Saul-Sehy 16 Comments

Last week I described the ultra-thrilling process of how high yield bond funds work. The reason I penned that particular post was simple. I was in the process of buying one.

In today’s entry, lets look “over my shoulder” to see the method I used to pick my new fund. Many people don’t get to see how someone with 16 years of professional experience chooses an investment in their portfolio. Choosing a high yield mutual fund is a little like exploring through a wasteland of worthless investments (as you’ll soon see), and I think there’s a few crucial basics beginners can learn from my adventure.

Why? Like reading a map, you’re going to be surprised by how straightforward and simple the process is. Buying funds isn’t complicated and you too can find a good mutual fund within minutes while feeling comfortable that you performed adequate due diligence.

The key part of the process is spending some good time with the map first. If you know what you’re looking for, exploring for the fund is the easy part.

Leading up to choosing a fund, I determined the following:

  1. I knew my end goal. I wasn’t just throwing money in the general direction of my problems or praying for high returns. I didn’t use a “more is better” approach. That usually lands investors in an ugly spot, when their greed turns profits to huge losses. I was looking for retirement, and needed to maintain at least a 6 percent return to get there.
  2. I had already determined my asset mix to reach my goal. On our podcast and in previous posts, I’ve discussed finding the appropriate diversified asset mix for your goals. Mine included high yield bonds, mostly because they have a history of achieving my target return.
  3. I knew how much money I needed in high yield bonds to meet my goal. Normally, I’m not a fan of mutual funds. But, because it was a small amount and a manager can oversee the process of avoiding defaults, I decided one mutual fund would do the trick. For more sizable chunks, I’d hire multiple managers or switch from a mutual fund to individual bonds.

Why is it important to determine these three criteria first?

Like deciding which size ice cream cone you’re getting, it’s best to look at your current situation, or waistline, first. Plus, there’s another, overreaching reason:

I’m lazy.

Could you imagine the horror of searching through a gazillion mutual funds in a trillion different asset classes to find the one that fit my needs? Why would I spend countless hours oogling different investments I’ll never buy. I want to narrow the search as much as possible before investing. Why waste all that time I could be watching Cake Boss or Millionaire Matchmaker sorting through countless asset classes that I’ll never use?

I’m not going to waste time searching for investments. I’ll figure out the map first and then choose the right vehicle to get me to my goal.

…and that, class, is how we reached this point: choosing the vehicle.

Let’s begin.

My search began at TD Ameritrade. That’s because the IRA holding the cash I was going to use is housed there. If you’re not familiar with IRA custodians, you have a choice between many different places. Some decide on a bank, others a financial brokerage firm. I chose TD Ameritrade because I’m comfortable choosing investments alone but appreciate their stock and bond tools. They aren’t the cheapest provider, but I’m comfortable with the fee structure.

Fees


Just like a trip to the grocery store, every asset search begins with a discussion of “how much is this going to cost.” In many cases, I don’t want a mutual fund at all because they’re expensive, but in the high yield asset class, I want one. I don’t want to guess if one of the companies I own is going to go bankrupt. I also don’t want to do the homework necessary to avoid picking a loser (remember the lazy part above?).

Some mutual funds manage your cash for a reasonable fee, while others might as well be carrying a gun and wearing a mask.

But they’re not the only robbers.

It turns out that TD Ameritrade also is in on the “let’s gouge our customer” game. They’ve forged deals with some fund companies to offer their mutual funds at a lower cost. To tell you just how much lower, I was originally eyeing a Pioneer high yield offering. Imagine my surprise when I found out that I’d have to pay $49 when I bought AND AGAIN when I sold. Ouch.

As an aside, why not just round this ridiculous fee to $50? Wouldn’t anyone dumb enough to pay $49 shrug at a dollar more? If they want to play the psychological game make it $49.99. They’re leaving $10 on the table. I should work for TD Ameritrade…..


Screening: Expenses


So, armed with the list of funds that are available on my platform, I visit TD Ameritrade’s mutual fund screener site. There are many of these all over the web. The Wall Street Journal has a good one, as do Morningstar, Yahoo and MSN.

I used TD Ameritrade’s own screener for one reason. The first screen for me should be called “funds that avoid the ridiculous fee.” Because that’s too obvious, they named it, “No trading cost fund list.”

Screening: Manager


The second screen is for manager. If I have a manager at all, I want one who’s a little seasoned, but different than most investors, I also don’t want one who’s crusty. A fund manager nearing retirement might be milking her reputation at this point. Well-known managers such as Bill Gross at PIMCO are going to survive a couple down years with their portfolio if they decide to take a mental vacation at this point in the game. I don’t want that person.

I want them hungry.

There is no “avoid managers who have been around too long” screen, so I’m stuck using one based on minimum tenure. I don’t want one with less than three years in the saddle, personally, so I choose that screen.

Screening: Star Rating

Like I said, I’m lazy. I want Morningstar to do most of the heavy lifting for me. Although I’m smart enough to know that many lower-ranked funds could do well next year, I don’t have the time to search through them all.

In other areas, where I’m looking for more than a consistent dividend check and a fairly stable value, I might screen for more complex areas. In high yield, that’s it.

I press the “search” button.

Examining the List.

Now I feel like a kid in a candy store. Laid out in front of me is a shortened list of candidates for the title of “good enough to examine up-close.”

My attention now turns to fund evaluation company Morningstar, where I’m going to dig into each fund in detail.

I’m particularly interested in:

  • how each fund performed against it’s competitors,
  • what the dividend looks like, and
  • how the fund is managed.

I dig into these areas quickly. Simple internet searches lead me to mines of information. I’m too lazy to waste time flipping through funds, but when I’ve found my potential targets, I dig in like a rib-lover at the barbeque cook-off.

Pile of banded $100 bill stacks

What Did I Choose?

Ultimately, the USAA High Income Fund won the day.

Why?

For an average fee of .90%, the dividend to me approaches 7% (6.93% as of this writing). The fund manager, R. Matthew Freund, has 21 years of experience (with USAA since 1994), so is mature yet not quite at retirement age. There’s been a co-manager named Julianne Bass since 2007, so there is younger blood overseeing day-to-day operations as well.

The fund has beaten the high yield sector over the past five years, but not by a ton. For the most part this fund’s performance has been slightly above or below the index. When it’s missed, it missed well above its asset category. It hasn’t had a major hiccup.

At this point, I like to guess what I’d rank the fund. I’d give it four stars out of five. It’s a winner, but not a thoroughbred. It won’t be the “hot thing” anytime soon. Perfect for this job.

Morningstar agrees, rating the fund four stars out of five. It’s an above average competitor with average fees and solid management.

Perfect. Often five star funds attract scads of assets, forcing me to look elsewhere as the management can’t invest all of the cash it’s attracted. I’m less concerned with the management of the fund over the past five years as I am over the next five. Because this fund isn’t meant to be the “go baby go” part of my portfolio, I’m fine with boring. In fact, I expect it and hope for it. Let’s get my 7% return so I can focus my energy elsewhere.

That’s how I picked the fund.

Complex? Nope.

I’d be willing to bet that this little 1000 word example is more homework than 95 percent of people complete when choosing investments. Even if a professional picks funds for you, there should be a list of screens you use to oversee picks.

It’s your portfolio. Take charge. It isn’t difficult.

(photo credit: Statue, Eusebius, Flickr;

Enhanced by Zemanta
Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: investment types, investment websites, low cost investing, money management, Planning, successful investing Tagged With: High-yield debt, Investment management, Morningstar, Mutual fund, PIMCO, TD Ameritrade, USAA, Wall Street Journal

High Yield Bond Investing for Beginners

April 24, 2012 by Joe Saul-Sehy 11 Comments

Imagine investing in a fund that built bigger and bigger dividends until you were ready to use them. Sound good?

I’ve always been a fan of high yield bonds as an asset class for this reason. My clients and I earned solid results by investing in these products.

Today, boys and girls, we’ll explain what a high yield bond is, how it reacts to different pressures and the method I’d recommend to buy a high yield bond if I were a beginner.


What is a High Yield Bond?


Let’s begin with the word “bond.”

Most people are comfortable with the idea of a stock. If you own stock in a company, congratulations! You are now the proud owner of a piece of that firm. How will you make money? Like any company owner, you’ll generally come out ahead as the company’s business prospects improve. If the company takes a downturn, you could stand to lose your entire investment.

A bond is better for people who don’t want that roller coaster ride. Instead, bond holders are more comfortable loaning a company money. The company gives you specific terms (for example: five years at a six percent interest rate), and you agree to loan them the money.

In essence, you aren’t a company owner. You’re Louie the Loan Shark. Sweet!

Graffiti of a grinning shark in sunglasses, a playful take on bond investors as lenders

How Do I Decide Which Bond to Buy?


Well, Louie the Loanshark, what’s the first question you’re going to ask if you’re loaning someone money?

That one’s easy: How likely is it that I’ll get my money back?

In the case of High Yield bonds, it’s pretty shaky. If these companies were regular people, they’d be the type that’ve had their American Express Card taken away and their house payment is two months behind.

When I said Loan Shark, I meant it.

So, when you see bad credit, what do you do? You jack up the interest rate. If I’m going to risk my money, I’m going to need to see a good return. High yield bonds are the highest returning bond type on the market. You’ll receive much higher returns than any other type of bond because you’re taking more risk.

High yield bonds used to be called junk bonds. To dress up the category, somebody decided “high yield” was a prettier name. I’d agree.


Is This Category Too Risky For Me?


Maybe. It depends on your goals. But let’s mitigate the risk of buying a single bond.

If you’re a new investor, I wouldn’t try to purchase an individual bond (loan money to one company). Frankly, the risks in that arena are too high for a beginner, unless you’re completely open to the risk of losing all of your capital.

In this case, I prefer a mutual fund. With a fund you have humans buying and selling positions on the open market. Fund managers diversify the portfolio like an ETF would, but also can sell when a certain company starts to turn for the worse. You don’t want to worry about that.


Let’s Talk About Performance and the Dividend


In high yield bond funds the dividend usually is classified as interest, so this asset class is best used in your tax sheltered plan (RRSP or IRA).

First, you can expect the value of your fund to fluctuate. With a high yield bond fund, I’ve always considered this the roll of the ocean. If I still own the shares  and they’re pumping out a dividend, I have one goal: make that dividend grow.

Therefore, I reinvest dividends.

That purchases more shares, which I reinvest in the mutual fund. I’m always looking at the size of my dividend payment that’s reinvested and asking “is it large enough to supplement my income yet?” Until it is, I continue to reinvest.

One of my clients pretended the dividend was a little man who worked alongside him each month. Every dividend would head back into the factory to help make the next payment a larger amount.


Popular High Yield Bond Investor Questions


How much should I invest?

With any investment, you begin by finding the return you need to meet your goal. For some investors, high yield bonds will be too risky for their portfolio. For others, they’ll need growth in their portfolio and high yield will rarely give you huge returns.

How risky is a high yield bond fund?

I present the risks of a high yield bond as “high” because I want investors to understand the risk versus other bonds. However, on a long-term risk/reward pyramid, high yield bonds are less risky than large cap stocks. If you’re comfortable investing in stocks, a high yield bond mutual fund historically has been less risky.

If I Don’t Have an IRA or RRSP Should I Still Invest?

I prefer to use tax advantaged investments outside of a tax shelter and tax-creating assets inside of shelters. High yield bonds are heavily taxed when compared to other asset classes that earn a similar return. You can use a high yield bond mutual fund outside of a tax shelter, but realize you’ll pay more tax than you will with many other investment classes.

How to I Find a Good High Yield Bond Mutual Fund?

Read our pieces on using Morningstar to find good funds:

Part I: Researching Mutual Funds (or how to cure insomnia)

Part II: Evaluate a Mutual Fund in 10 Minutes


Not only will you see past performance, but this website will tell you about fees and how much you’ll need to invest to meet fund minimums.


(Photo Credit: Payday Loan Store, Swanksalot, Flickr; Loan Shark, Jesse Wagstaff, Flickr)


Okay, that’s my story. Do you use high yield in your portfolio? Are there criteria or tools you use to choose high yield bonds that are appropriate for a new investor that weren’t presented here? We’d love to hear them.

Photo of Joe Saul-Sehy
Joe Saul-Sehy

Joe is a former financial advisor and media representative for American Express and Ameriprise. He was the “Money Man” at Detroit television WXYZ-TV, appearing twice weekly. He’s also appeared in Bride, Best Life, and Child magazines, the Los Angeles Times, Chicago Sun-Times, Detroit News and Baltimore Sun newspapers and numerous other media outlets.  Joe holds B.A Degrees from The Citadel and Michigan State University.

joesaulsehy.com/

Filed Under: investment types, passive income, successful investing

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6
  • Next Page »

Follow Us

Search this site:

Recent Posts

  • Can My Savings Account Affect My Financial Aid? by Tamila McDonald
  • 12 Ways Gen X’s Views Clash with Millennials… by Tamila McDonald
  • What Advantages and Disadvantages Are There To… by Jacob Sensiba
  • Call 911: Go To the Emergency Room Immediately If… by Stephen Kanaval
  • 7 Weird Things You Can Sell Online by Tamila McDonald
  • 10 Scary Facts About DriveTime by Tamila McDonald
  • How to Avoid NJ Exit Tax by Jacob Sensiba

Copyright © 2026 · News Pro Theme on Genesis Framework